Last editorial review: October 7, 2026
401(k) Vesting: Schedules, Employer Contributions, and Job Changes
401k vesting determines when employer-paid retirement contributions become yours. This page is for employees reviewing a plan or considering a job change; the next step is to compare the vested and total balances on your statement with the schedule in your Summary Plan Description.
10 min read
Practice investing with Finelo
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
Want to learn more?
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
401k vesting determines when employer-paid retirement contributions become yours. This page is for employees reviewing a plan or considering a job change; the next step is to compare the vested and total balances on your statement with the schedule in your Summary Plan Description.
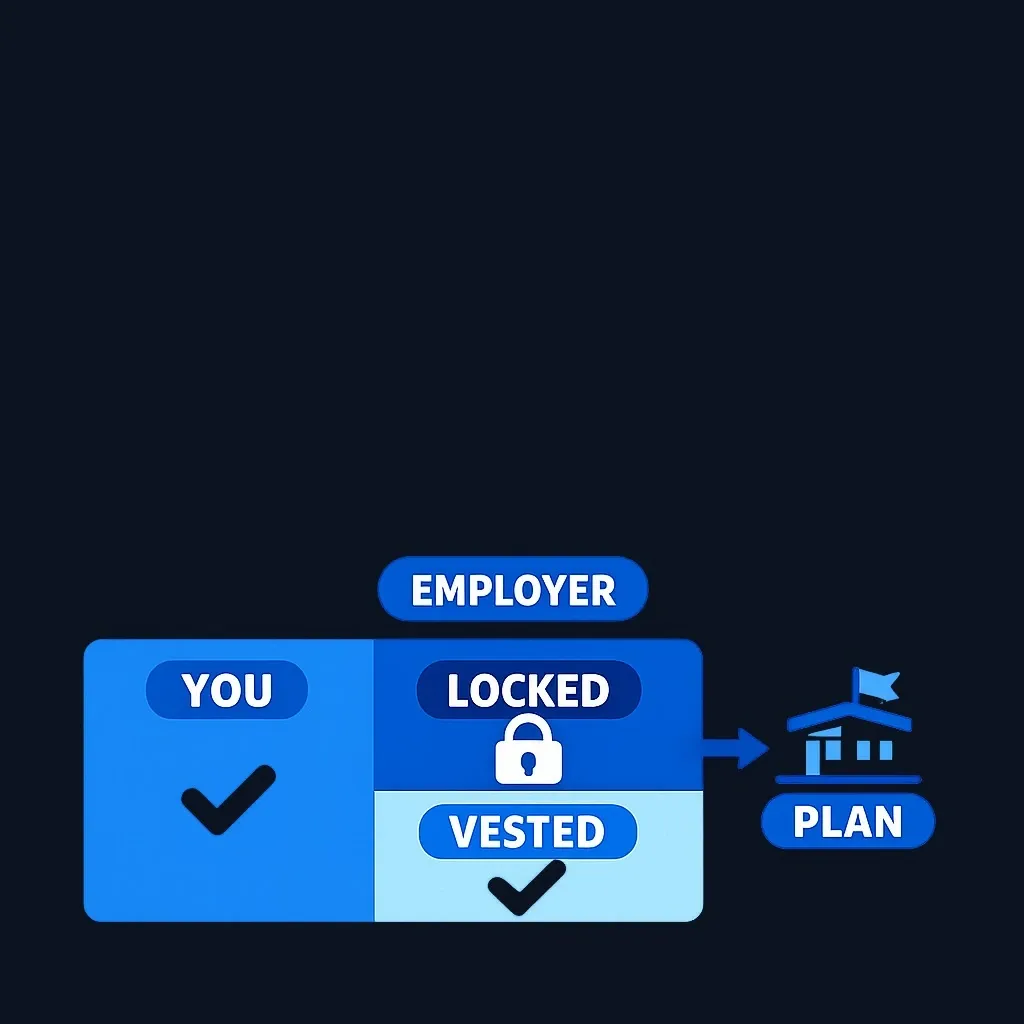
Vesting is the plan rule that determines when employer-paid retirement contributions (for example, matching or profit‑sharing) become your legal property; your own salary deferrals and any earnings on them are always 100% vested immediately (U.S. Department of Labor). If you leave a job before employer contributions are vested, you typically cannot keep the unvested portion.
What is 401(k) Vesting?
Vesting describes when employer contributions to your retirement account become nonforfeitable — in other words, when those contributions legally belong to you. Your pre‑tax or Roth payroll deferrals and the investment gains they produce are fully yours from the moment they are made (U.S. Department of Labor).
Why vesting matters
- Portability: Vesting determines how much of your retirement account you can take if you change jobs.
- Compensation value: Unvested employer contributions are conditional pay until they vest.
- Timing and negotiating power: Knowing your vesting timeline helps when deciding whether to stay for a milestone or request different compensation.
Concrete next step: request your plan’s Summary Plan Description (SPD) and your most recent account statement from HR or the plan administrator. The SPD contains the official vesting table and definitions your plan uses.
Finelo publishes financial education for people building practical money skills. This content is educational and does not recommend a transaction; employment and retirement choices involve tradeoffs and possible tax consequences.
Types of 401(k) Vesting
Employers typically use one of a few qualitative approaches to vesting for employer contributions. These are plan design choices, not changes to your own contributions (which are always fully vested) (U.S. Department of Labor).
| Type | How ownership increases | Practical effect if you leave early |
|---|---|---|
| Immediate vesting | Employer contributions are fully yours as soon as they’re deposited | Employer match is portable right away |
| Cliff vesting | Nothing vests until a single service milestone, then employer funds vest all at once | Leave before the milestone ⇒ likely forfeit; leave on/after ⇒ keep all |
| Graded vesting | Employer ownership increases in steps until fully vested | You keep a portion proportional to completed service; remaining portion may be forfeited |
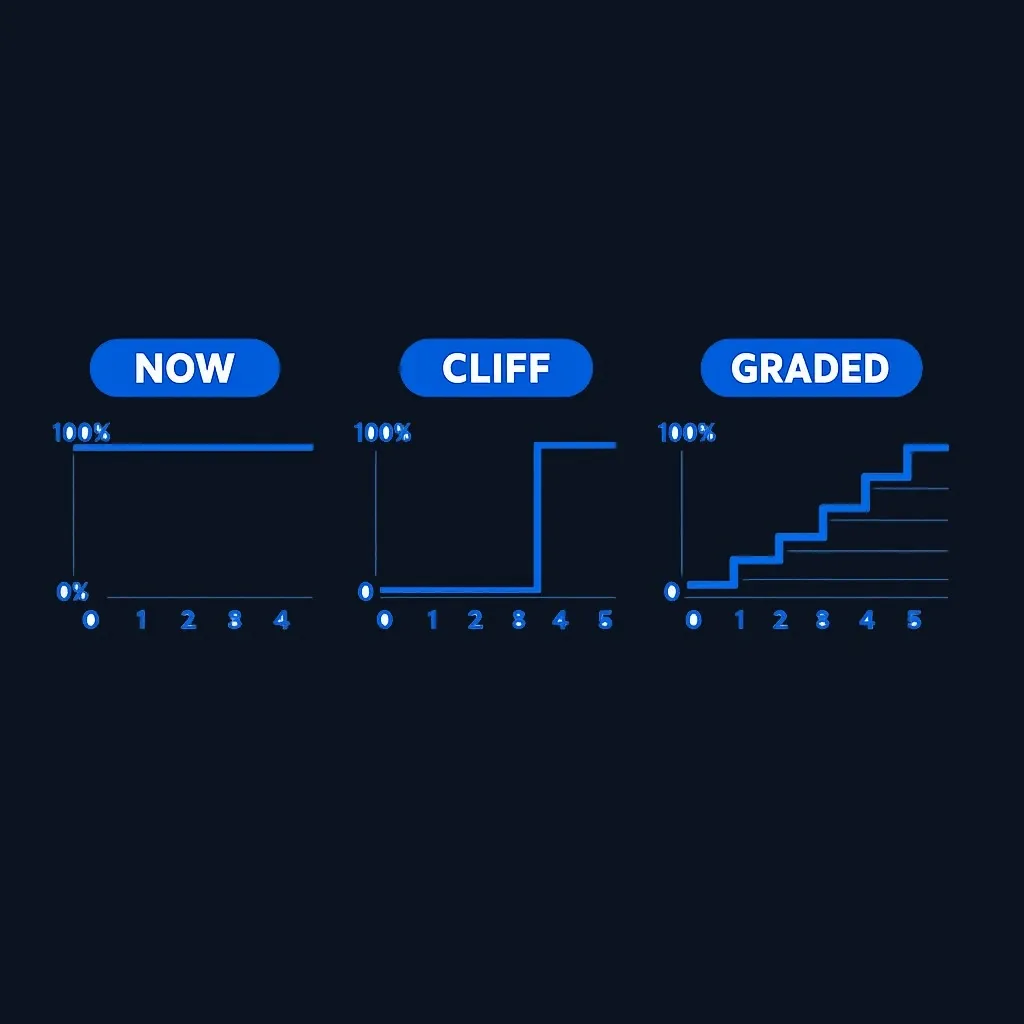
Decision implication: immediate vesting maximizes portability; cliff and graded schedules are common employer retention tools. Always read your SPD to confirm the exact timing and definitions that apply to you.
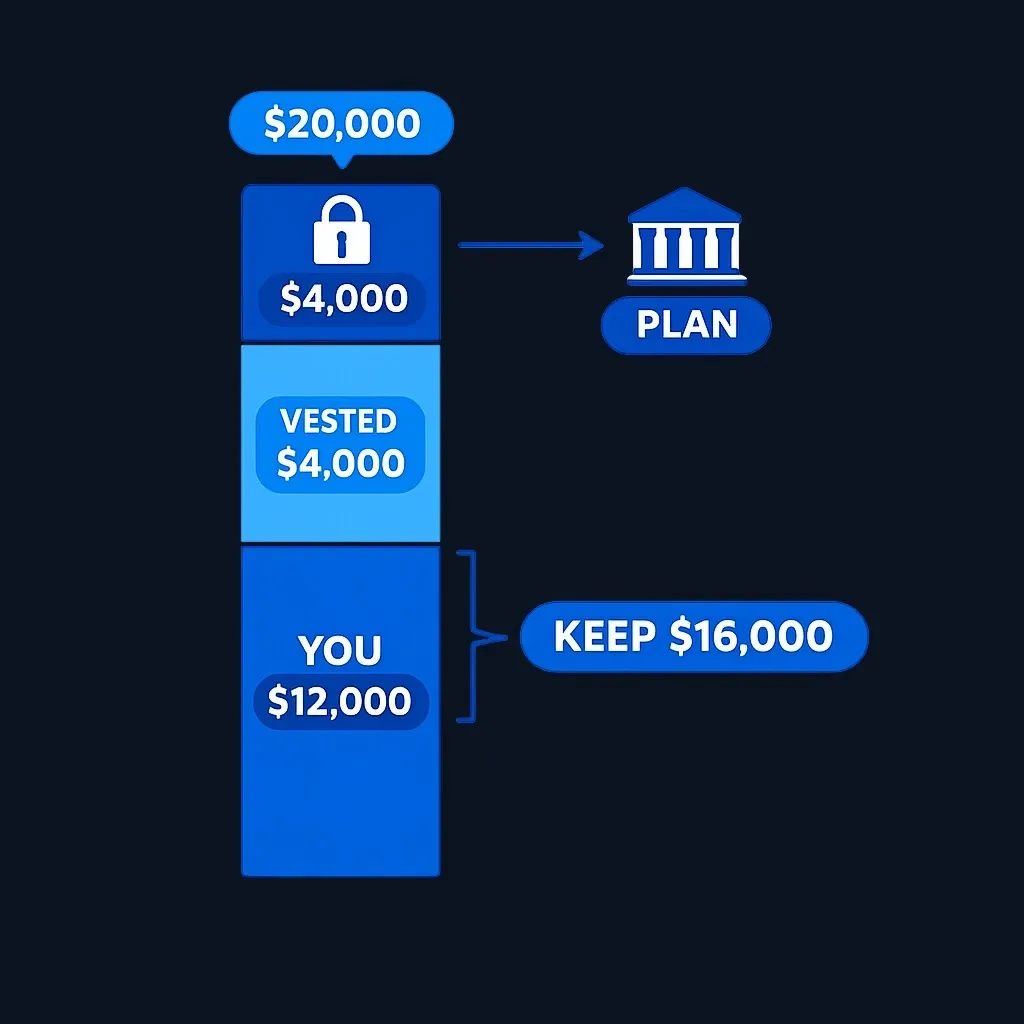
Example (worked): if your account shows a $2,000 employer match and your vested percentage is 40%, the vested employer portion is $800 and the remaining $1,200 is currently unvested and subject to plan forfeiture rules.
How 401(k) Vesting Works
Vesting is a legal feature written into the plan document and enforced via payroll and plan records. Understanding the mechanics helps you avoid surprises when you change jobs or when plan terms change.
Core mechanics
- Ownership split: Your salary deferrals (and their earnings) are fully vested; employer contributions may be subject to a vesting schedule (U.S. Department of Labor).
- Service measurement: Vesting usually depends on "service" as defined in the SPD (examples include years, anniversary dates, or hours worked). Confirm how your plan counts service and partial years.
- Forfeitures and plan use: Plans handle unvested amounts according to the SPD—common treatments include using forfeitures to offset future employer contributions or plan expenses. Check your plan documents for specifics.
- Rollovers and portability: Only vested amounts are your property and therefore the amounts you can roll into another qualified plan or an IRA when you leave.
- Administrative timing: When employers deposit contributions, the posting date and the plan’s effective-date rules can affect whether a contribution counts toward a vesting milestone.
Common mistakes and fixes
- Mistake: Assuming a match is vested. Fix: verify your vested percentage on your statement.
- Mistake: Ignoring break‑in‑service rules (leave of absence, unpaid gaps). Fix: ask HR for a written explanation of how breaks affect vesting.
- Mistake: Delaying rollover paperwork after separation. Fix: act promptly to avoid forced distributions or missed rollover windows.
Concrete action: ask the plan administrator for a current vested vs. total balance summary and written answers about how they measure service and handle rehires or leaves.
Vesting Schedules Explained
A vesting schedule is the table or rule in the SPD that maps your service to a vested percentage. Employers set those schedules in the plan document; the SPD is the authoritative source.
How to read your vesting table
- Locate the vesting section or table in the SPD or plan summary.
- Note the definition of a “year of service” (calendar year, anniversary, or hours-based).
- Check if partial years or certain leaves count toward service.
- Look for acceleration language that might speed vesting for events (if any).
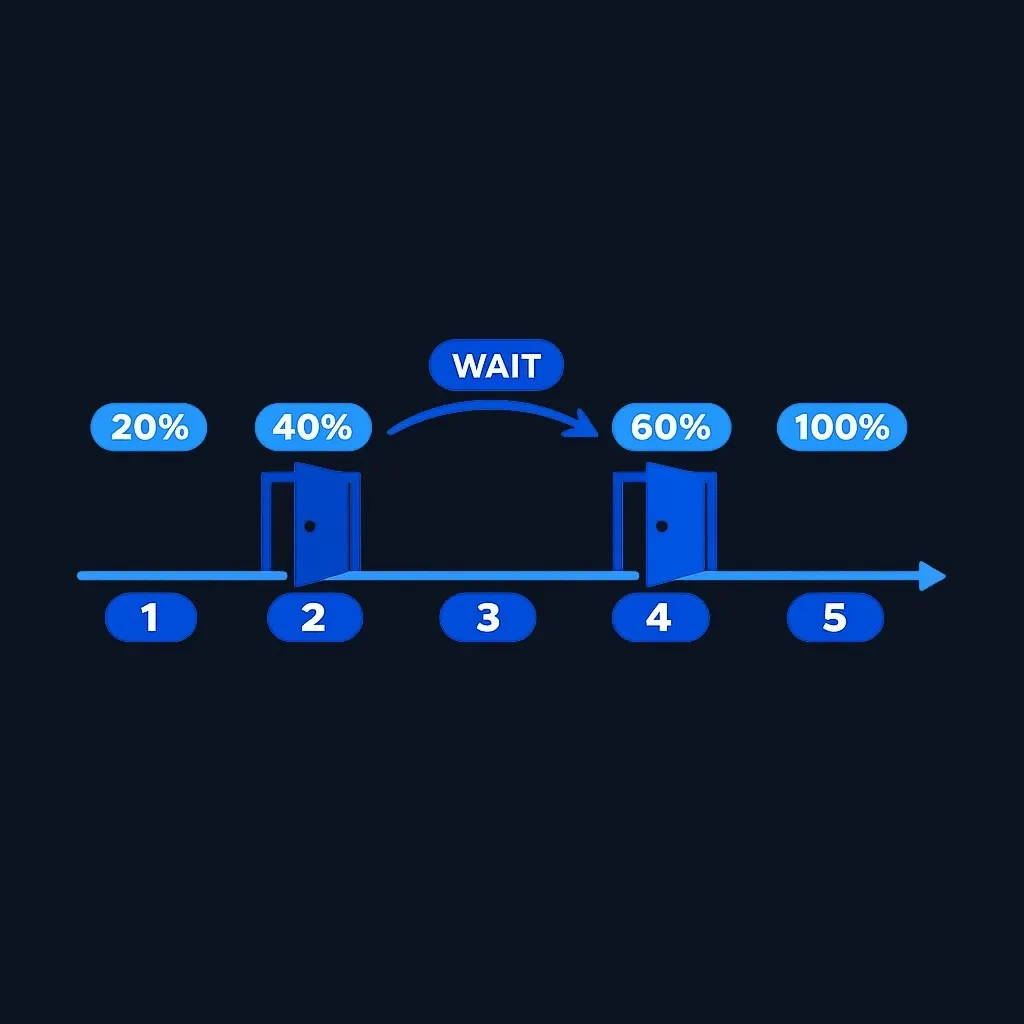
Interpretation tip: a graded schedule provides partial ownership at intermediate points, while a cliff schedule offers full ownership only after a single milestone. Read the SPD terms for exact dates (for example, whether a contribution posted the day before separation counts toward vesting).
Illustrative scenarios
- Short‑tenure employee: on a cliff schedule, leaving days before the milestone may forfeit all employer contributions; on a graded schedule, the employee might keep part of them.
- Long‑tenure employee: under many schedules, longer service increases the employer portion you permanently own.
Caveat: plan language varies. If a vesting milestone affects a hiring or retention decision, obtain the SPD language and any employer commitments in writing.
Events Triggering Full Vesting
Some plans include provisions that accelerate vesting when specific events occur. These provisions differ by plan and are not guaranteed; confirm any claimed acceleration in the SPD or a written employer agreement.
Common plan-level triggers (plan-specific)
- Retirement as defined in the plan (age and service requirements may apply).
- Disability if it meets the plan’s definition.
- Plan termination or an employer decision to freeze or end the plan.
- Certain corporate events if the plan contains a change‑in‑control or acquisition clause.
Negotiation and verification
- If an acceleration clause is material to your decision (for example, tied to a sale), request the exact SPD wording or a signed agreement.
- For senior hires, consider negotiating explicit acceleration or partial immediate vesting and get it in writing.
Practice investing with Finelo
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
401k vesting decisions before a job change
Vesting affects whether you accept an offer, when you might leave a job, and how you approach rollovers or retirement planning. Treat unvested employer contributions as conditional compensation in your decision calculus.
Three practical decisions
- Accepting an offer: faster vesting increases the immediate value of employer contributions. If vesting is slow, weigh that conditional value against alternatives like a higher salary or a signing bonus.
- Staying vs. leaving: if you are close to a vesting milestone, staying until it passes might increase the amount you keep. Estimate the net benefit after taxes and opportunity cost.
- Changing jobs: know your vested amount, the rollover options for vested funds, and any timing deadlines before separation.
Compare-offers framework (quick)
- Estimate total employer contributions you expect over your intended tenure.
- Apply the plan’s vesting percentages for that tenure to find expected vested value.
- Compare that conditional value to other compensation (salary, bonus, equity).
- Factor in mobility: if you expect to move often, prioritize immediate portability.
Negotiation checklist
- Ask for partial immediate vesting or a shorter initial vesting period.
- Request a cash signing bonus instead of a long vesting timeline.
- For senior roles, propose written acceleration tied to specific events.
Practical caveat: employers are not obligated to alter standard plan provisions; they may prefer cash or bonus tradeoffs to contractual vesting changes.
Decision framework
Use this five-step framework when vesting materially affects a hiring, retention, or rollover decision.
- Define your objective: portability, immediate cash value, or long‑term retirement growth.
- Document your position: obtain a statement showing vested vs. total balance and the SPD.
- Time‑horizon check: estimate how long you realistically expect to stay versus vesting milestones.
- Compare value: treat unvested employer contributions as conditional compensation and weigh alternatives like higher base pay or signing bonuses.
- Execute: if you leave, arrange rollovers for vested funds promptly and complete required forms.
Quick scenario (worked example)
- You have $5,000 in employee deferrals (100% vested) and a $2,000 employer match. If your plan shows you are 50% vested, your vested employer portion is $1,000 and your total vested balance is $6,000. Use that figure when comparing an offer or deciding whether to stay for a milestone.
Negotiation tips
- Offer alternative tradeoffs employers may accept, such as a one‑time signing bonus in lieu of faster vesting.
- For senior hires, request clear, written acceleration clauses.
- If vesting is tied to corporate events, demand precise definitions in the agreement.
What to know before deciding
Pre-action checklist
- Get your latest plan statement showing vested vs. total balances.
- Obtain the Summary Plan Description (SPD) and read the vesting table.
- Ask the plan administrator how the plan counts service, treats breaks/rehire, and posts contributions.
- If leaving, learn rollover options and any deadlines to avoid automatic distributions.
- When negotiating, insist any promised vesting changes be documented in writing.
Common pitfalls to avoid
- Relying on oral promises — always get written documentation.
- Assuming deposits post immediately or count for vesting the way you expect — verify posting rules.
- Overlooking how forfeitures are used — confirm whether they offset future employer contributions or pay plan costs.
FAQ
What does 401k vesting mean?
Vesting is the rule that determines when employer contributions in your retirement plan become your property. Your own salary‑deferral contributions and the earnings on them are always fully vested immediately (U.S. Department of Labor).
How does graded vesting work?
Graded vesting phases in employer ownership over time in steps until you are fully vested. The SPD specifies the step sizes and timing; check your plan document for the exact schedule that applies to you.
What is cliff vesting?
Cliff vesting delays employer ownership until a single service milestone, at which point employer contributions become fully vested. The SPD will list the cliff timing and the plan’s service‑counting rules.
What happens to unvested employer contributions if I leave?
Unvested employer contributions are not your property until they vest; plans commonly treat unvested amounts per the SPD’s forfeiture rules. Confirm with the plan administrator how the plan handles forfeitures and whether they reduce future employer contributions or offset plan expenses.
Conclusion and Next Steps
Key takeaways
- Your own contributions and their earnings are always 100% vested (U.S. Department of Labor).
- Employer contributions may vest over time according to the plan’s vesting schedule; unvested portions can be forfeited.
- Read the SPD, confirm your vested percentage, and document any employer promises in writing.
Actionable next steps
- Request your SPD and the latest account statement showing vested vs. total balances.
- Ask HR or the plan administrator exactly how service is measured and whether any acceleration clauses apply.
- If a vesting milestone affects your job decision, model the vested value versus alternative compensation (salary, bonus) before negotiating.
If you want a simple worksheet to estimate vested value from your plan statement, make a copy of a blank spreadsheet and enter: total employer contributions × vested percentage = vested employer amount. Adjust the model for different tenure assumptions to compare offers or retention choices.
Finelo educational disclaimer: Finelo provides general financial education, not personalized financial, investment, tax, or legal advice. Financial decisions can involve risk and loss. Verify current rules and product terms with the linked official sources and seek a qualified professional when a decision depends on your individual circumstances.
Sources and Further Verification
InvestingU.S. GuideFinancial Education
Practice investing with Finelo
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Investing
Stock Scanner vs Screener: Key Differences Explained
A stock scanner watches the market continuously for live events and unusual activity; a stock screener filters a static universe of stocks by written criteria (ratios, indicators, timeframes) so you can evaluate candidates. For example, Benzinga describes its product as a "full‑blown, real‑time scanner" for saved scans and…
Finelo Team
Investing
Stock Alert Apps: Features, Costs, and How to Compare
Stock alert apps watch prices, indicators, or news and notify you when pre-set conditions happen — letting you act without constant screen time. Many traders use alerting tools to monitor breakouts and time entries, for example Benzinga Pro’s alerting is relied on by day traders Benzinga Pro. This…
Finelo Team
Investing
Social Investing Apps: Features, Risks, and How to Compare
Finelo is an investment-learning and financial-education product. This page helps readers evaluate a social investing app without treating crowd activity as a trade instruction.
Finelo Team