Last editorial review: October 7, 2026
How to Save for a Car: A Step-by-Step Guide
Save for a car by setting a clear target (price + taxes + fees + buffer), dividing that total by your timeline to get a monthly savings target, and automating transfers into a dedicated account. Pair a low-risk savings vehicle with a written budget and monthly tracking to…
8 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
Save for a car by setting a clear target (price + taxes + fees + buffer), dividing that total by your timeline to get a monthly savings target, and automating transfers into a dedicated account. Pair a low-risk savings vehicle with a written budget and monthly tracking to stay on schedule. This article shows how to set the target, cut spending, automate savings, and choose where to hold the money.
What to know before deciding
Before you pick a target or account, decide whether you want to buy with cash, make a large down payment, or finance. The Consumer Financial Protection Bureau offers tools to evaluate vehicle affordability and auto‑loan decisions to avoid surprises when choosing between cash and credit Consumer Financial Protection Bureau.
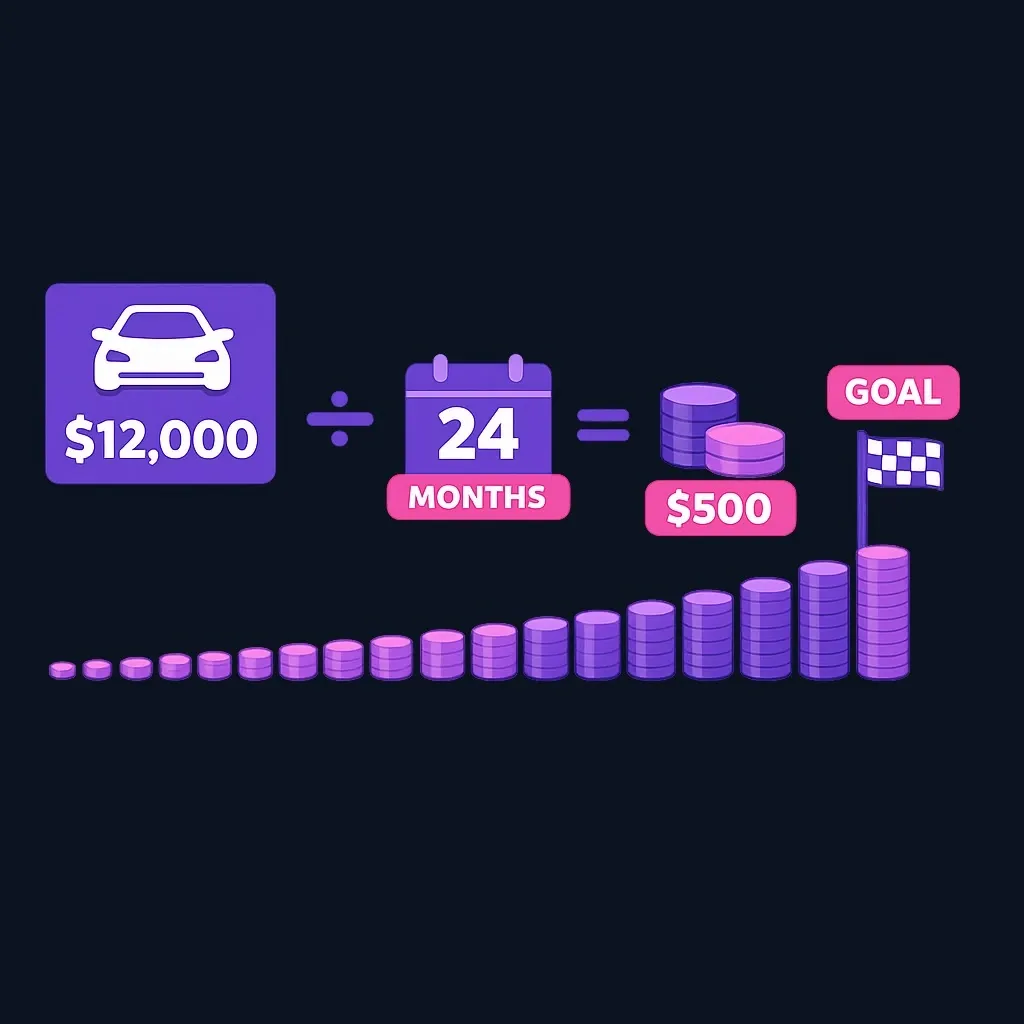
Setting a Realistic Savings Goal
How to calculate the total target
- List the car price you expect to pay (use multiple listings to get a realistic range).
- Add taxes, registration, dealer fees, and any immediate maintenance you expect.
- Add a short-term buffer (e.g., 5–10%) for negotiation or unexpected items.
- Decide on a down payment target if you plan to finance.
Monthly target formula (simple):
- Monthly savings = Total target ÷ Number of months until purchase.
Worked example A (hypothetical): If your total target is $12,000 and you want to buy in 24 months, save $12,000 ÷ 24 = $500 per month.
Worked example B (illustrative arithmetic): saving $4,750 over 12 equal monthly deposits requires about $396 per month; saving $4,500 over 12 months requires $375 per month. These are planning examples, not recommended down-payment amounts or vehicle budgets.
Decision points and caveats
- Short timeline → higher monthly amount or consider lower-priced cars.
- Long timeline → allows slower monthly saves but exposes you to rate/price changes.
- If you plan to finance, aim for a larger down payment to reduce interest paid; verify loan details before assuming monthly-payment savings Consumer Financial Protection Bureau.
Creating a Budget: Where to Cut Costs
Quick budgeting checklist
- Track 1–2 months of expenses to see patterns.
- Prioritize: rent, utilities, minimum debt payments, groceries, transportation.
- Identify 3 adjustable items to reduce (e.g., subscriptions, dining out, streaming).
- Redirect savings: funnel every identified cut toward your car fund.
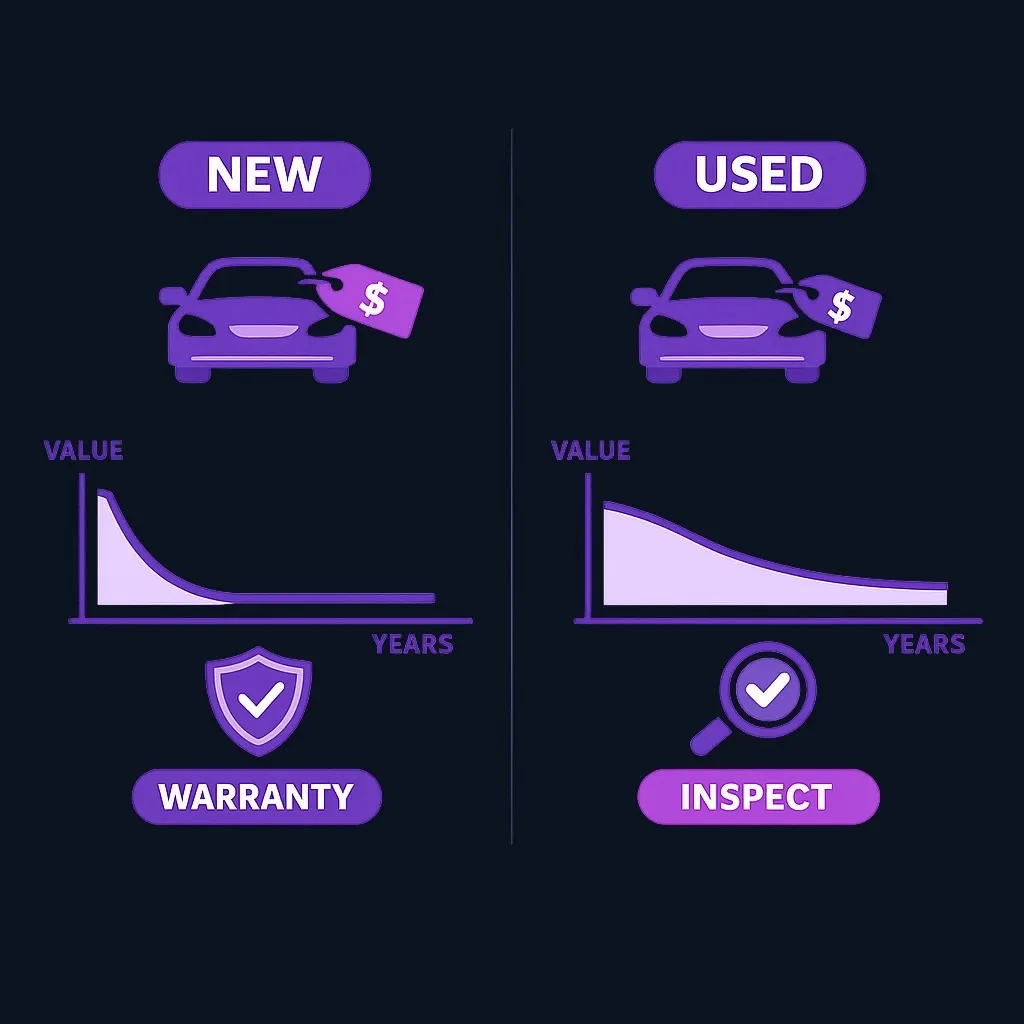
Practical cuts that add up:
- Pause nonessential subscriptions for 3–6 months.
- Cook more meals at home; set a weekly dining-out budget.
- Temporarily sell unused items for a one-time boost to the fund.
Budget template you can copy:
- Monthly take-home pay: $____
- Fixed essentials (rent, utilities, loans): $____
- Variable essentials (food, gas): $____
- Wants and subscriptions: $____
- Monthly available for car savings = Income − (fixed + variable + wants)
If you’re worried about spending the money elsewhere, making the savings process obvious—such as a dedicated account name or an auto-transfer rule—helps people stick to goals AAA coverage of loud budgeting.
Automating Your Savings: Make It Effortless
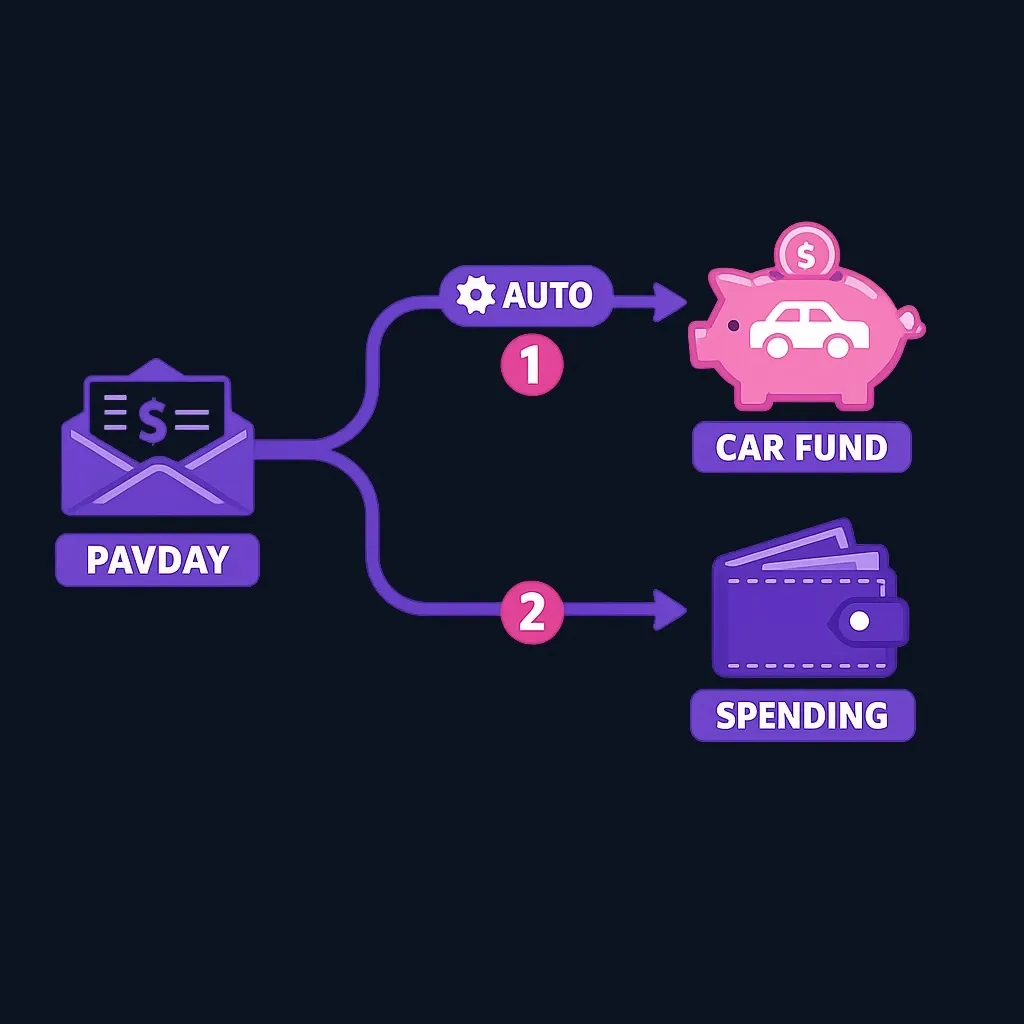
Automatic transfers make saving consistent and reduce temptation. If your checking account or employer supports direct deposit splits, route a fixed amount to a dedicated car savings account each payday. Chase recommends automating transfers and increasing the saved amount when possible to remove the temptation to spend and to know when you'll hit your target Chase: How can I save up for a car?.
Practical steps
- Open a dedicated savings account (label it “Car Fund”).
- Set up an automatic transfer for each pay period.
- Schedule a monthly progress check and increase the transfer after pay raises or one-time windfalls.
Caveat: If you expect to buy within a few months, prioritize liquidity and avoid locking money into long-term products.
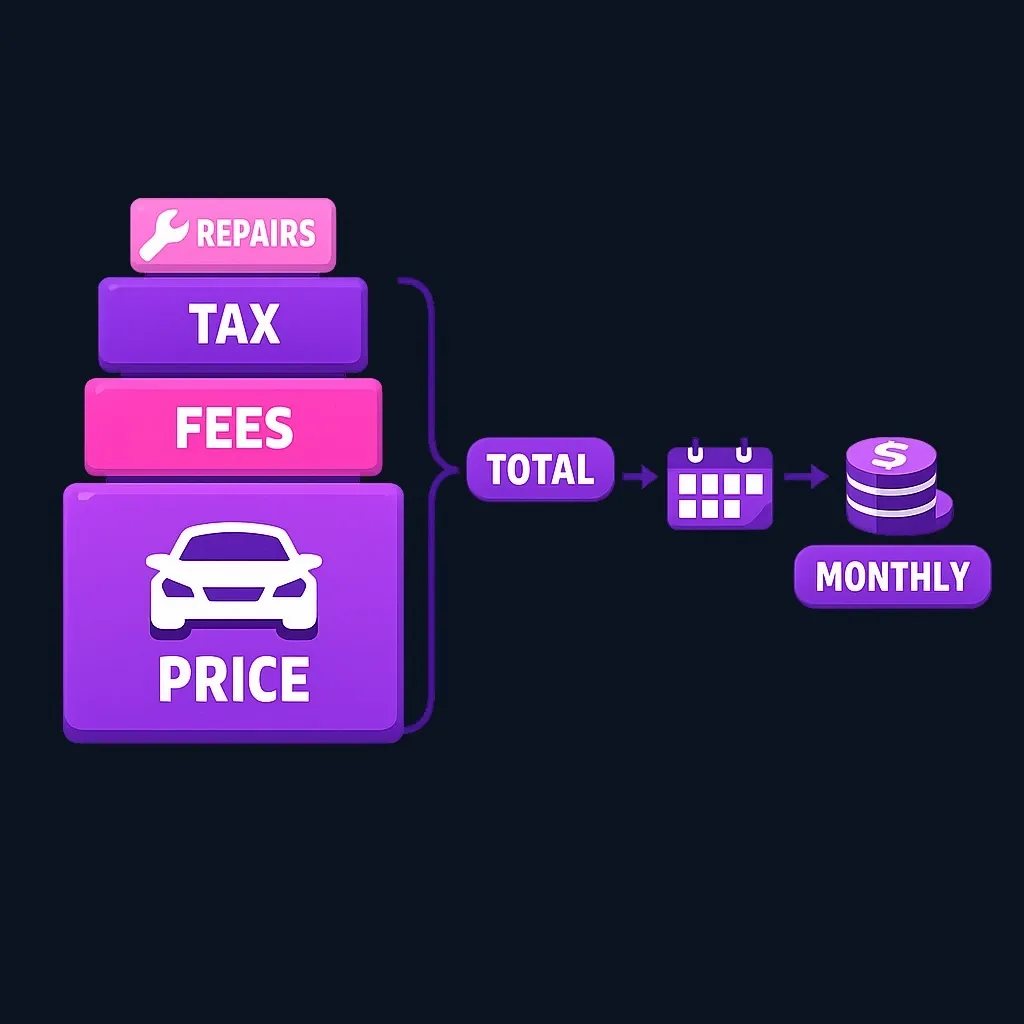
Understanding the Total Cost of Car Ownership
Owning a car involves more than the purchase price. Plan for:
- Insurance premiums.
- Routine maintenance and repairs.
- Fuel and parking.
- Registration, taxes, and inspection fees.
- Possible loan interest if you finance.
Evaluate affordability by comparing estimated monthly ownership costs to your budget and any loan payments you might take on; the CFPB provides resources to help weigh borrowing costs and loan terms Consumer Financial Protection Bureau.
Tip: Build a maintenance rainy-day subfund (for example, several hundred dollars) so unexpected repairs don’t derail your car fund.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Best Ways to Save for a Car
Use a low‑risk, liquid place for funds you’ll need within a few years. Common choices and tradeoffs:
| Option | Liquidity | Typical use case | Risk |
|---|---|---|---|
| Standard savings account | High | Short timeline, immediate access | Very low |
| High‑yield savings account | High | Keep pace with inflation; short to medium term | Low |
| Short-term CD (certificate of deposit) | Low–medium | Fixed timeframe, slightly higher yield | Low (penalty for early withdrawal) |
| Cash sweep or brokerage cash | High | Temporary holding before investing or buying | Low, but check protections |
Notes:
- Choose a high-yield savings account if you want a better return than a basic checking account while keeping immediate access. Always check current rates on the bank’s site before deciding.
- Avoid market investments (stocks, long-term mutual funds) if your purchase is within 1–3 years; short-term market volatility can reduce the funds when you need them.
Real-Life Case Studies: Successful Car Savings Plans
Below are three illustrative scenarios (numbers are examples you can adapt).
Scenario 1 — Short-term cash purchase
- Goal: $6,000 in 12 months → monthly = $500.
- Strategy: Move $250 from paychecks + $250 from cutting dining out and two subscriptions. Automate transfers to a named savings account.
Scenario 2 — Down-payment + small loan
- Goal: $10,000 car, 20% down = $2,000 down payment in 8 months → monthly ≈ $250.
- Strategy: keep a near-term down payment in a liquid, low-risk account whose fees, withdrawal limits, rate, and deposit-insurance status you have verified; compare loan terms only after you know the actual vehicle price and cash available.
Scenario 3 — Longer timeline for newer car
- Goal: $24,000 in 36 months → monthly ≈ $667.
- Strategy: Combine automated savings, occasional overtime pay, and sell a high-value unused item to shorten timeline.
Each scenario shows how adjusting timeline, target, and cuts changes monthly needs. Use the monthly target formula to test different timelines.
Decision framework
Use this simple checklist when making tradeoffs:
- Timeline: When do you need the car? (<6 months, 6–24 months, >24 months)
- Liquidity need: Do you need immediate access to funds?
- Risk tolerance: Can your savings ride out short-term losses? (If no, avoid market investments.)
- Target composition: Full cash vs. down payment + loan?
- Contingency: Do you have a repair/maintenance buffer after purchase?
How to pick a path quickly:
- If timeline < 12 months → use a high‑yield savings or checking with autosave.
- If timeline 12–36 months and you want a small extra return → high‑yield savings or short-term CDs with laddering.
- If timeline > 36 months and you can tolerate swings → consider low-cost diversified investments, but only for funds you can leave invested (this is general educational guidance; consider talking to an advisor).
FAQ
What is the best way to save for a car?
The best way depends on your timeline. For purchases under three years, prioritize liquidity and low risk—use a dedicated savings account and automate contributions. For longer timelines, you can consider vehicles with modest risk for higher expected returns but accept possible short-term losses.
How much should I save for a down payment?
Down payments are sometimes discussed as percentages, but there is no universal target. Base the amount on the vehicle’s out-the-door price, written loan offers, taxes and fees, trade-in value, emergency-cash needs, and total cost. For planning, divide your chosen dollar target by the months remaining; $4,500 over 12 months equals $375 per month.
What expenses should I consider when budgeting for a car?
Include insurance, routine maintenance and repairs, fuel, parking, registration and taxes, and any loan interest. Don’t forget a short-term buffer for unexpected repairs.
How can I automate my savings?
Use direct deposit splits, set recurring bank transfers to a dedicated savings account, or use your bank’s autosave features to move money automatically each payday Chase: autosave guidance.
Conclusion: Your Next Steps Toward Car Ownership
- Pick a realistic target (price + fees + buffer).
- Choose a timeline and compute monthly savings with the simple formula: Total ÷ Months.
- Open a dedicated account and automate transfers.
- Trim three monthly expenses and redirect that cash to the car fund.
- Revisit your plan every 3 months and adjust if income or priorities change.
If you want a structured budget you can copy, start with the template above and adapt the numbers to your income and timeline. For help comparing loans or checking financing affordability, see consumer resources on auto loans Consumer Financial Protection Bureau.
Verification note: Definitions, product capabilities, rates, thresholds, and market-data conventions can change. Recheck the linked official source on the date you act, record the methodology and timestamp used, and distinguish educational examples from live prices or personalized recommendations.
Sources and Further Verification
Financial LiteracyU.S. GuideFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
What is the 50/30/20 Rule and How to Implement It
If you search for "what is the 50 30 20 rule," it’s a simple budgeting guideline that divides after-tax (take-home) income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt reduction Consumer Financial Protection Bureau. Use it as a starting template, not…
Finelo Team
Financial Literacy
What is a Grace Period on a Credit Card?
A credit-card grace period is the time between the end of a billing cycle and the payment due date when new purchase balances may not accrue interest if you pay the statement balance in full by the due date. This is the standard definition used by the Consumer…
Finelo Team
Financial Literacy
A Complete Guide to Student Loan Cosigner Release
A cosigner release is a lender-offered process that removes a cosigner’s legal obligation from a private student loan once the primary borrower meets the lender’s conditions—typically a run of on-time payments and a credit check of the borrower alone CFPB. Check your loan documents and contact your servicer…
Finelo Team