Last editorial review: October 7, 2026
Income-Producing Assets: Types, Risks, and How to Compare
Income producing assets are investments that generate recurring cash payments—rent, interest, dividends, or royalties—without selling the underlying asset. Typical examples include dividend-paying stocks, bonds, rental real estate, REITs, and business or royalty income; dividend stocks are a common starting point for income strategies FINRA. Read on for how…
8 min read
Practice investing with Finelo
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
Want to learn more?
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
Income producing assets are investments that generate recurring cash payments—rent, interest, dividends, or royalties—without selling the underlying asset. Typical examples include dividend-paying stocks, bonds, rental real estate, REITs, and business or royalty income; dividend stocks are a common starting point for income strategies FINRA. Read on for how to choose, build, and stress-test an income-focused portfolio.
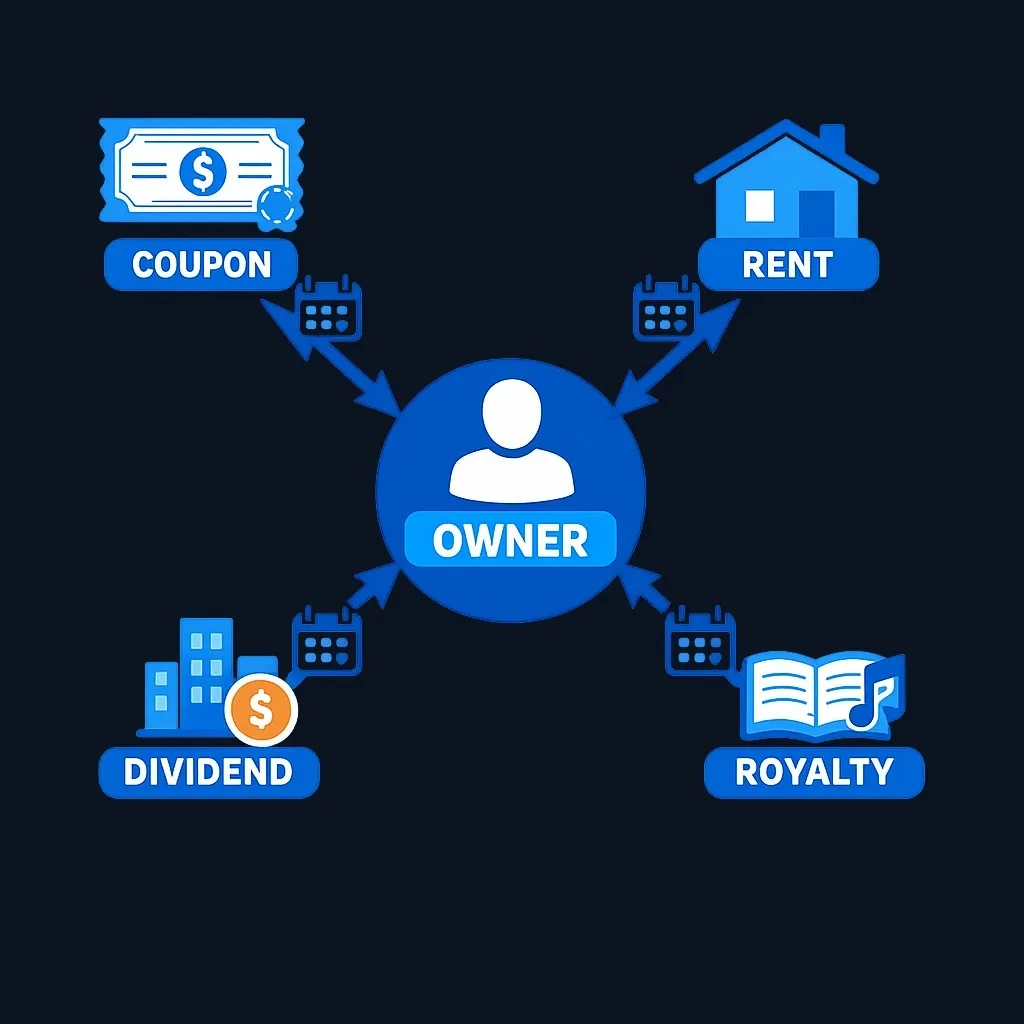
Introduction to Income Producing Assets
Income producing assets deliver periodic cash flow from the asset itself instead of relying only on price appreciation. That cash flow can pay living expenses, fund reinvestment, or be held as a liquidity buffer. The key distinctions to understand are the income source (rent, coupon, dividend, or profit), how predictable payments are, and the asset’s liquidity and management burden. After this guide you should be able to list common income asset types, spot principal tradeoffs, and apply a simple framework to pick assets that match your income needs.
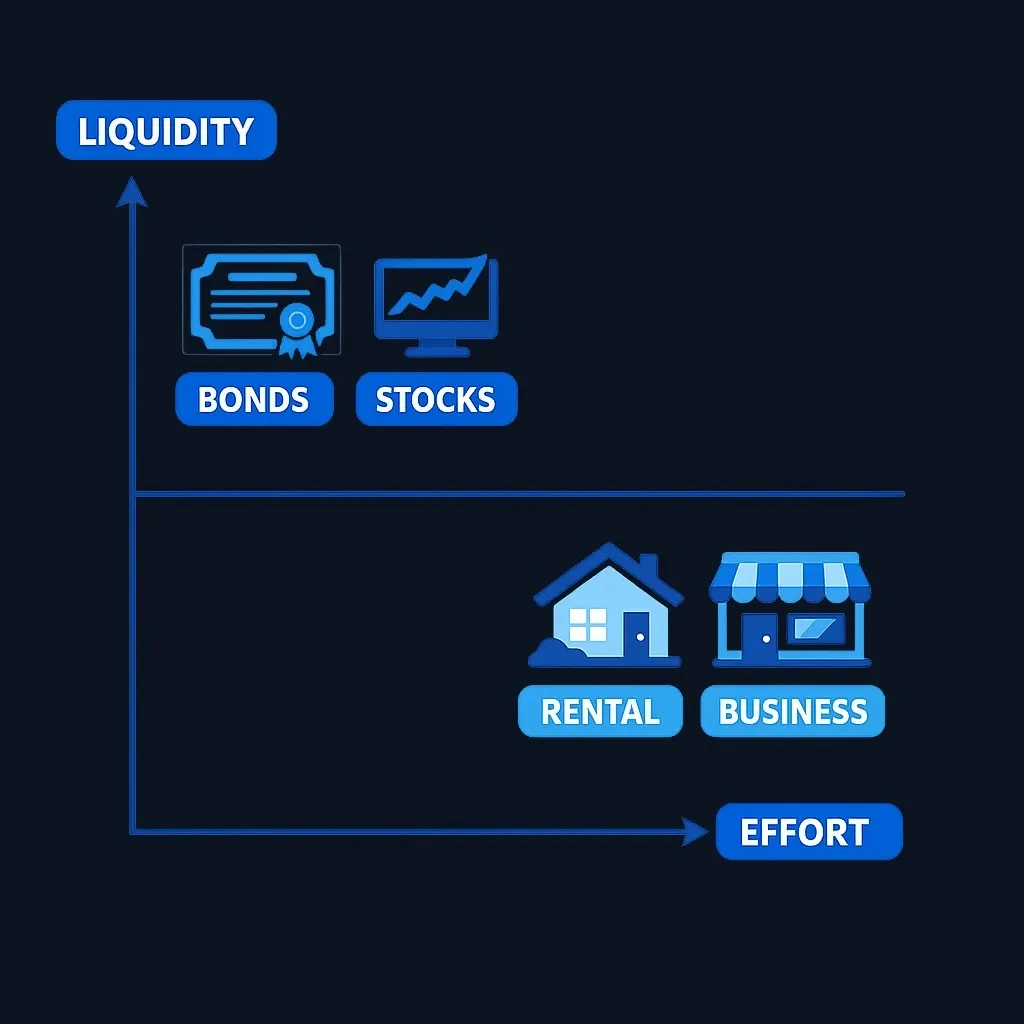
Types of Income Producing Assets
Below is a compact comparison to map asset types to common investor priorities: income frequency, management effort, liquidity, and typical risk drivers. Treat this table as a decision checklist, not a promise of yield or performance.
| Asset type | Typical income source | Common frequency | Management effort | Typical liquidity | Primary risk drivers |
|---|---|---|---|---|---|
| Dividend-paying stocks | Company dividends | Often quarterly | Low–moderate | High (public markets) | Dividend cuts, market volatility |
| Bonds & other fixed income | Interest (coupon) | Semiannual or periodic | Low | Moderate–high (market-dependent) | Interest-rate and credit risk |
| Rental real estate | Tenant rent | Monthly | High (operations) or moderate with manager | Low–moderate | Vacancies, repairs, local market |
| REITs & property funds | Distributions/dividends | Quarterly or monthly | Low–moderate (public REITs) | High (public REITs) | Property market, leverage |
| Business income / royalties | Operating profits or royalties | Varies | High (active) or low (passive royalties) | Varies widely | Operational and demand risk |
| Annuities (income riders) | Contracted payouts | Monthly or scheduled | Low after purchase | Low (often illiquid) | Inflation exposure, fees, issuer credit |
Note: dividend-paying stocks are a commonly used income tool; see FINRA’s overview for educational context on dividend stocks FINRA.
Practical takeaway: match the asset’s payment timing, liquidity, and hands-on needs to your cash-flow timing and willingness to manage.
What to know before deciding
Educational note: this content is educational and not financial advice. Investing involves risk, including loss of principal. Consult a licensed professional about tax and investment choices.
Why investors add income assets
Income assets create predictable cash flow that can replace or supplement wages, support reinvestment for compound growth, or reduce the need to sell holdings in down markets. For investors nearing retirement, reliable distributions help convert accumulated capital into usable income.
Main tradeoffs and risks
- Income is not guaranteed; payouts can change with issuer or operating performance.
- Fixed nominal payments can lose purchasing power during inflationary periods.
- Illiquid assets (rental property, private businesses) can take time and cost to convert to cash.
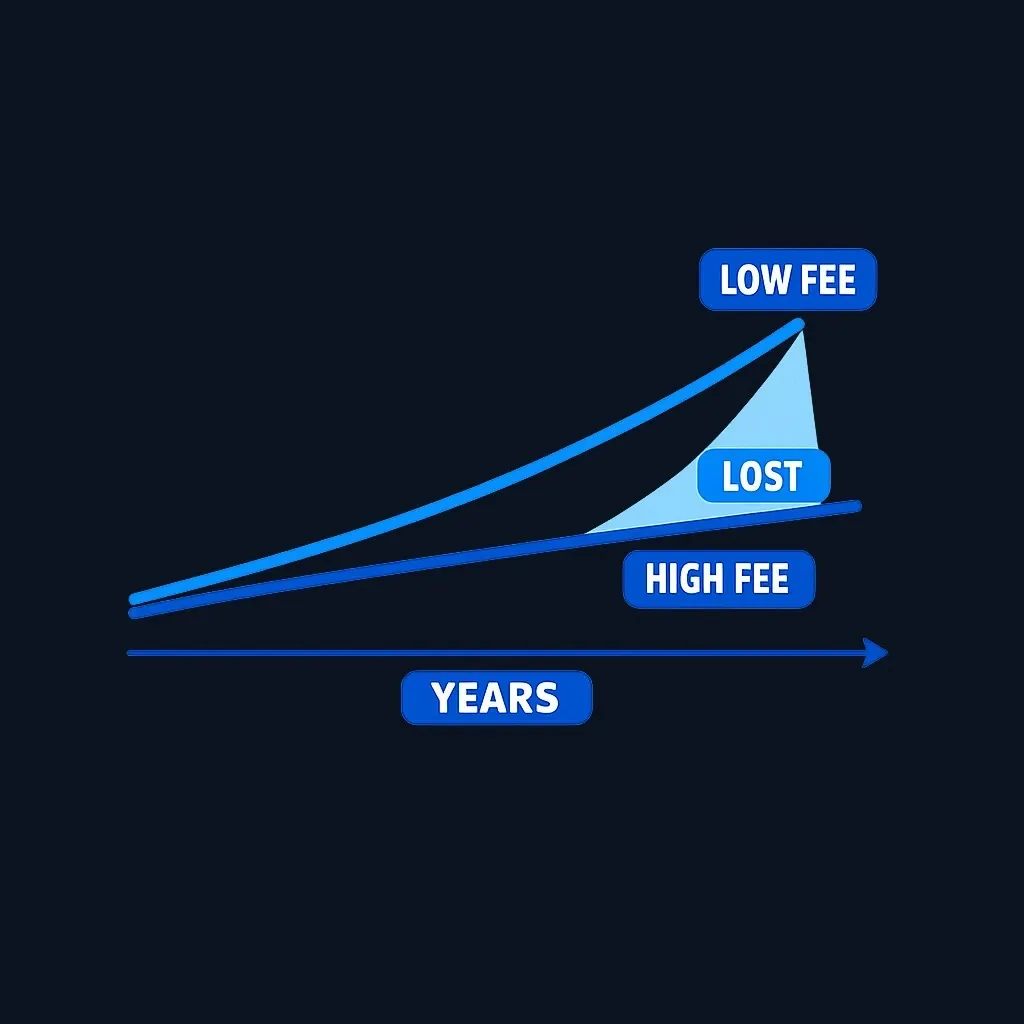
- Management costs and fees (property repairs, fund expense ratios) reduce net income.
Tax and structure considerations
Different income types can face different tax treatments (ordinary income, qualified dividends, passive-activity rules). Account type matters: placing tax-inefficient income inside tax-advantaged accounts can improve after-tax results. For specific tax treatment, consult a tax professional.
Practical checks before committing money
- Time horizon: match asset liquidity to when you’ll need the cash.
- Emergency reserve: keep several months of liquid savings before relying on illiquid income.
- Fees and structure: read fund prospectuses, property lease terms, and annuity contracts so fees don’t unexpectedly erode yield.
Practical red flags: chasing headline yields without reviewing underlying cash flow, assuming past payouts continue, or ignoring total return when you need capital preservation.
Strategies for Building an Income-Focused Portfolio
This section gives actionable constructions and allocation thinking a beginner can apply.
Core approaches
- Laddered fixed income: stagger maturities to smooth reinvestment and reduce sensitivity to rate changes.
- Dividend core + satellite: hold broad dividend or bond funds as a stable core and add small satellites (REITs, rental property) for extra yield.
- Cash-flow-first budgeting: calculate the monthly income you need, then size positions to meet that need after taxes and buffers.
- Total-return overlay: combine income assets with growth assets and withdraw a sustainable percentage, letting growth replace or support income over time.
A simple starting allocation exercise
- Define the net monthly income you want from investments.
- Allocate a safety-first portion to liquid, lower-volatility income (short-duration bonds, broad bond ETFs, dividend ETFs).
- Allocate a smaller portion to higher-yield but less liquid or higher-effort assets (REITs, rental properties).
- Maintain an emergency reserve to avoid forced sales during shortfalls.
Checklist for building your plan
- Goal: spending vs. reinvesting?
- Time horizon: short (<5 years), medium, long (10+ years)?
- Liquidity need: monthly cash vs. discretionary income?
- Risk tolerance: how much drawdown can you accept?
- Complexity: willing to manage property/business or prefer funds?
Practical tip: start with diversified public funds to learn cash-flow patterns before moving to individual properties or private businesses.
Practice investing with Finelo
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
Decision framework
Use this three-step framework to pick income assets that fit your situation.
Step A — Define the income objective
- Living expenses now: prioritize stable, liquid income and a larger cash buffer.
- Supplemental income: accept some volatility for higher expected yield.
- Retirement income: blend inflation protection and dependable distributions.
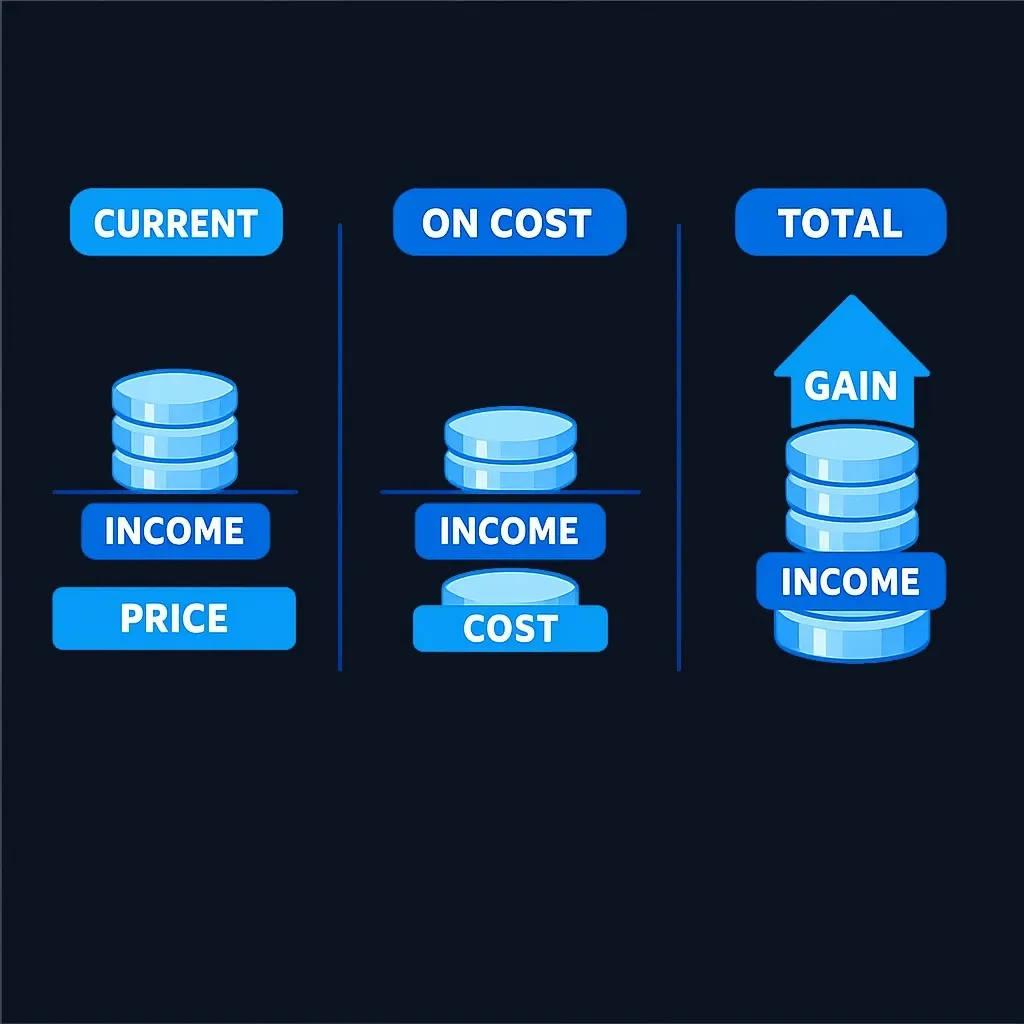
Step B — Map asset properties to objective
- Need monthly dependable cash → prefer liquid, scheduled payers (short-term bonds, dividend ETFs, certain REITs).
- Want higher yield and accept hands-on work → consider rental real estate, private loans, or business income.
- Tax sensitivity → favor account wrappers or municipal bonds where appropriate; consult a tax advisor.
Step C — Size and stress-test positions
- Calculate a target payout or withdrawal rate that fits your horizon.
- Stress-test scenarios: dividend cuts, rent vacancies, or rising rates; confirm reserves cover shortfalls.
- Rebalance periodically to preserve the intended income/risk profile.
Decision checklist (fillable)
- Objective declared: _______
- Required monthly income (net of taxes): _______
- Liquidity buffer (months): _______
- Starting allocation: conservative / balanced / aggressive
- Management plan: DIY / outsourced
- Review cadence: monthly / quarterly / annually
Next steps (practical)
- If starting small: open diversified income ETFs or bond funds and track distributions for 6–12 months.
- If considering property: run a pro forma (expected rent − expenses − vacancy allowance) and require a reserve.
- Keep a simple ledger of gross income G, operating/fees/taxes O, then compute net cash flow = G − O. Use that to size required allocations.
Real-Life Case Studies (scenario templates)
We provide three practical, anonymous scenarios you can adapt. Treat numbers as templates, not predictions.
Scenario A — Low-maintenance monthly supplement
- Goal: $X/month net.
- Path: short-duration bond funds + dividend ETFs to provide quarterly and monthly cash.
- Implementation: estimate blended net yield, divide annual required income by net yield to size allocation. Monitor distributions and fees quarterly.
Scenario B — Active higher-yield approach (rental property)
- Goal: higher net yield, accept ops work.
- Path: buy one or two small rental units and hire a property manager.
- Implementation: build a pro forma with rent, taxes, insurance, maintenance, management fee, and a vacancy cushion. Require immediate cash reserve for repairs and unexpected vacancy.
Scenario C — Retirement income ladder
- Goal: staged income certainty over years.
- Path: laddered bonds (for near-term cash), dividend-paying equities (for growth + income), and selected annuity or insurance contracts if guaranteed payouts are desired.
- Implementation: match bond maturities to known cash needs and use equity income to cover long-term inflation exposure.
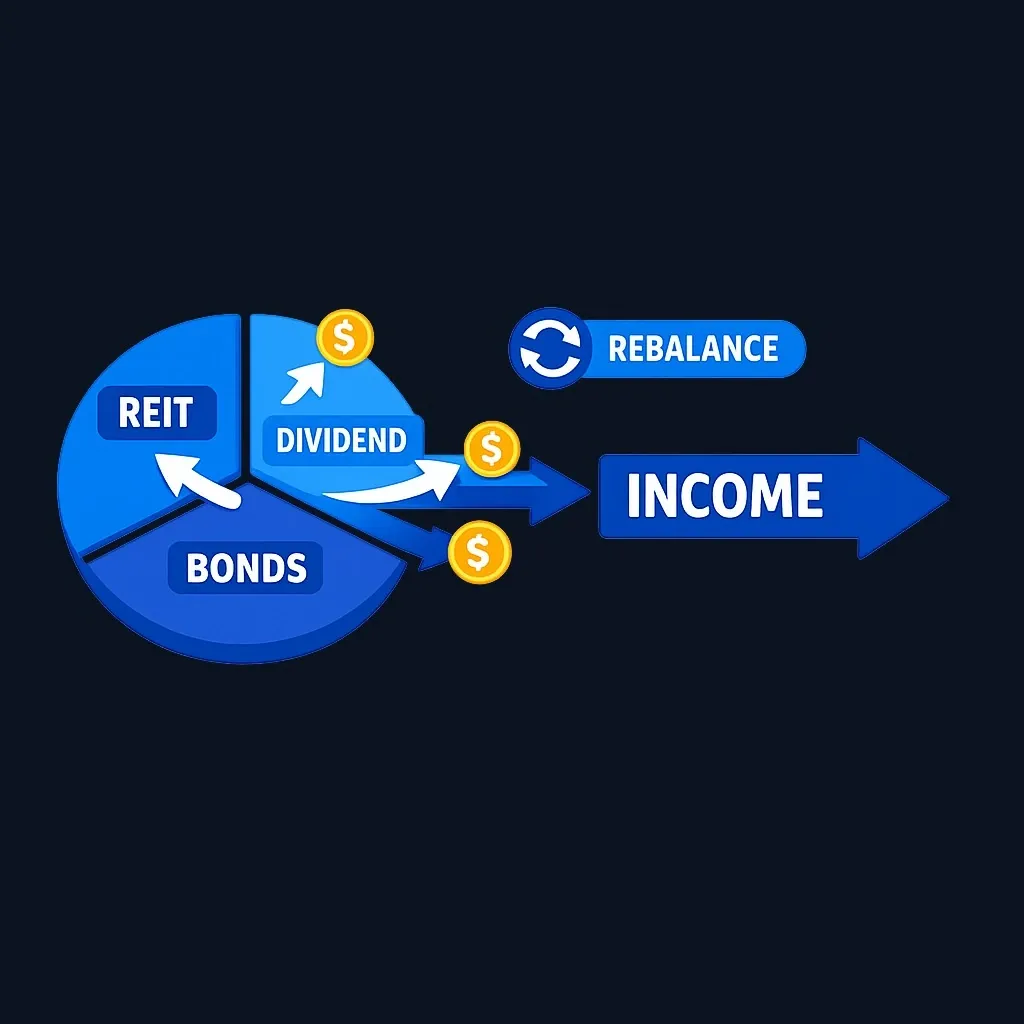
Worked-example template (use with your numbers)
- Expected gross income per year (G): input your estimate.
- Annual operating fees/taxes (O): input estimate.
- Net annual income = G − O.
- Required allocation = (Target annual net income) / (Annual net yield). Apply actual quotes from funds, property pro formas, or advisor estimates when you run numbers.
FAQ
What are income-producing assets?
Income-producing assets regularly generate cash flow—for example, dividends from stocks, interest from bonds, rent from property, or royalties. Stocks that pay dividends are commonly used by investors seeking predictable income FINRA.
How do I start investing in income-producing assets?
Clarify your income objective and horizon, set an emergency reserve, then begin with diversified liquid income funds (bond ETFs, dividend ETFs) while you learn cash-flow behavior. For real estate or businesses, run a cash-flow pro forma and consider professional help (property manager, CPA, or financial advisor).
What are the main risks of income-producing assets?
Risks include reduced or stopped payments (dividends, rents), credit or issuer default, interest-rate-driven price changes, inflation erosion of fixed payments, and liquidity constraints when selling illiquid assets. Management costs and fees also reduce net income.
Can I rely solely on income-producing assets for retirement?
Relying only on income assets can work for some people but depends on required spending, inflation exposure, tax efficiency, and whether income sources suffice in worst-case scenarios. Many investors combine income assets with growth assets and contingency plans to handle sequence-of-returns and inflation risks.
Conclusion: practical next steps
Summarize your objective, pick one immediate action, and track results. Example actions: open a diversified bond or dividend ETF to learn cash-flow timing, or run a rental pro forma if you plan property investing. Keep a six- to twelve-month ledger of actual cash flows and management costs to adapt allocations based on real experience.
Sources and Further Verification
InvestingU.S. GuideFinancial Education
Practice investing with Finelo
Build practical investing skills with guided lessons, simulator practice, and structured challenges.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Investing
Stock Scanner vs Screener: Key Differences Explained
A stock scanner watches the market continuously for live events and unusual activity; a stock screener filters a static universe of stocks by written criteria (ratios, indicators, timeframes) so you can evaluate candidates. For example, Benzinga describes its product as a "full‑blown, real‑time scanner" for saved scans and…
Finelo Team
Investing
Stock Alert Apps: Features, Costs, and How to Compare
Stock alert apps watch prices, indicators, or news and notify you when pre-set conditions happen — letting you act without constant screen time. Many traders use alerting tools to monitor breakouts and time entries, for example Benzinga Pro’s alerting is relied on by day traders Benzinga Pro. This…
Finelo Team
Investing
Social Investing Apps: Features, Risks, and How to Compare
Finelo is an investment-learning and financial-education product. This page helps readers evaluate a social investing app without treating crowd activity as a trade instruction.
Finelo Team