Last editorial review: October 7, 2026
Pay Off a Mortgage or Invest? Costs, Risks, and Tradeoffs
If you value guaranteed, interest‑cost savings and lower monthly obligations, prioritize paying down your mortgage; if you can reasonably expect higher after‑tax investment returns than your mortgage interest rate and you’re comfortable with market risk, investing will often grow your net worth faster. This page shows how to…
12 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
If you value guaranteed, interest‑cost savings and lower monthly obligations, prioritize paying down your mortgage; if you can reasonably expect higher after‑tax investment returns than your mortgage interest rate and you’re comfortable with market risk, investing will often grow your net worth faster. This page shows how to weigh rates, taxes, liquidity, risk tolerance, and emotional factors so you can make a reasoned choice.
Introduction: Understanding the dilemma
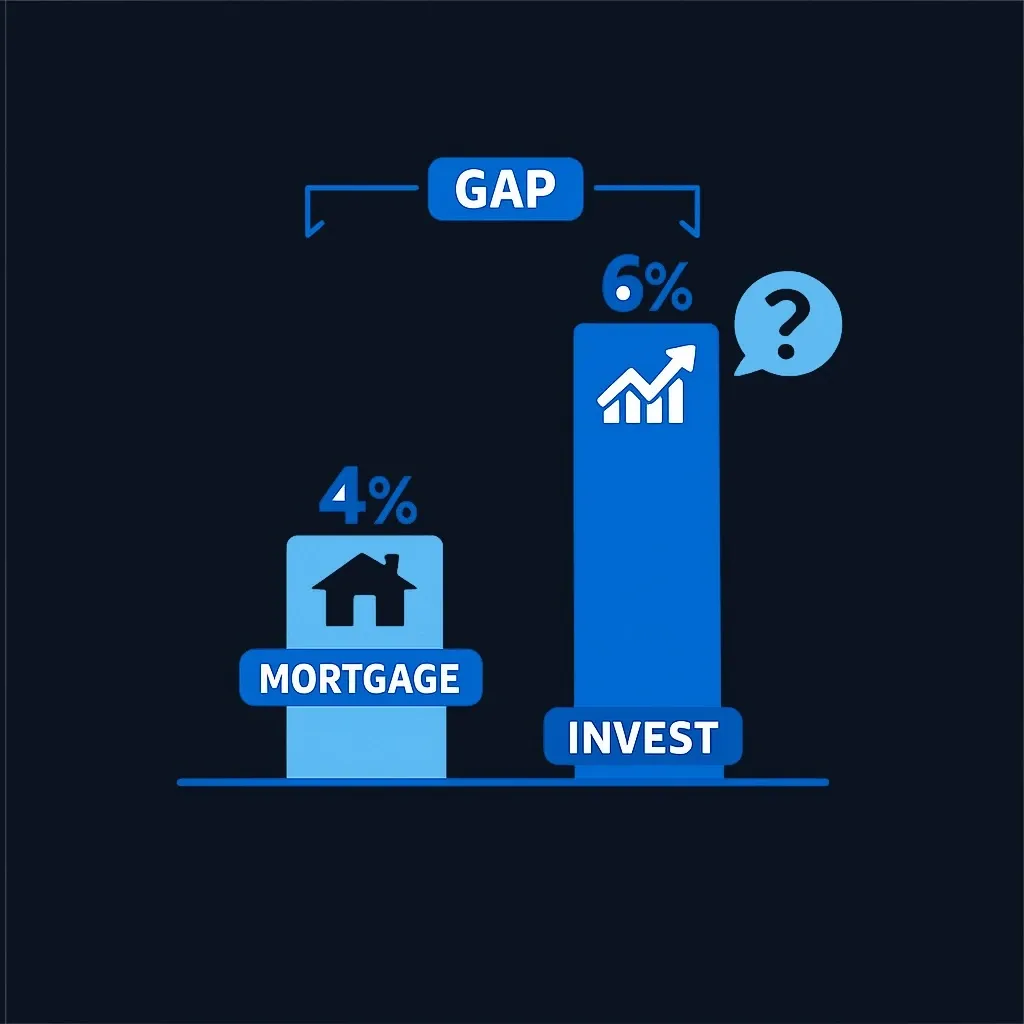
Most households routinely face a simple-sounding choice: use extra cash to accelerate mortgage payoff, or channel that money into investments (retirement accounts, taxable brokerage accounts, or other assets). The two options trade off a guaranteed reduction in interest costs and debt burden against the potential for higher but uncertain market returns. A savings account or short‑term cash buffer is different from investing; savings are usually for short‑term goals and emergencies while investing targets long‑term growth (Investor.gov on saving vs. investing). This article helps you translate that tradeoff into a decision you can act on.
After reading you will be able to:
- Identify the financial metrics that matter for your situation.
- Run simple, transparent comparisons between mortgage payoff and investing.
- Use a checklist and worked examples to pick a default plan you can test and adjust.
What to know before deciding
Make these facts and constraints explicit before making any comparison.
-
Your mortgage interest is a guaranteed (risk‑free) rate of return when you prepay the loan. Paying $1,000 toward principal saves you interest at your mortgage rate over the remaining term. Treat that saved interest as the effective return on the payoff option.
-
Investment returns are uncertain and typically measured over long periods; short windows can produce very different outcomes. Maintain an emergency fund separate from any investing or payoff plan (Investor.gov separation of saving and investing).
-
Liquidity matters. Extra principal payments are illiquid — once paid, it’s not easy to get that cash back without a refinance or sale. Investments, depending on type, can be more liquid.
-
Taxes change outcomes. Some mortgage interest may be deductible depending on your jurisdiction and filing circumstances; investment returns can be taxed as ordinary income, qualified dividends, or capital gains. Tax effects are personal and vary by location and filing status — treat them as modifiers, not primary drivers.
-
Other debts and goals come first. Pay off very high‑interest debt (credit cards, payday loans) before deciding between mortgage payoff and investing.
-
Time horizon and goals matter. If retirement is decades away, historically equities have outperformed mortgages after inflation and taxes in many markets — but past performance is not a guarantee. If your horizon is short, the certainty of interest savings can be more attractive.
-
Psychological and cash‑flow benefits (reduced monthly payment, feeling of safety) have real value and are part of the decision.
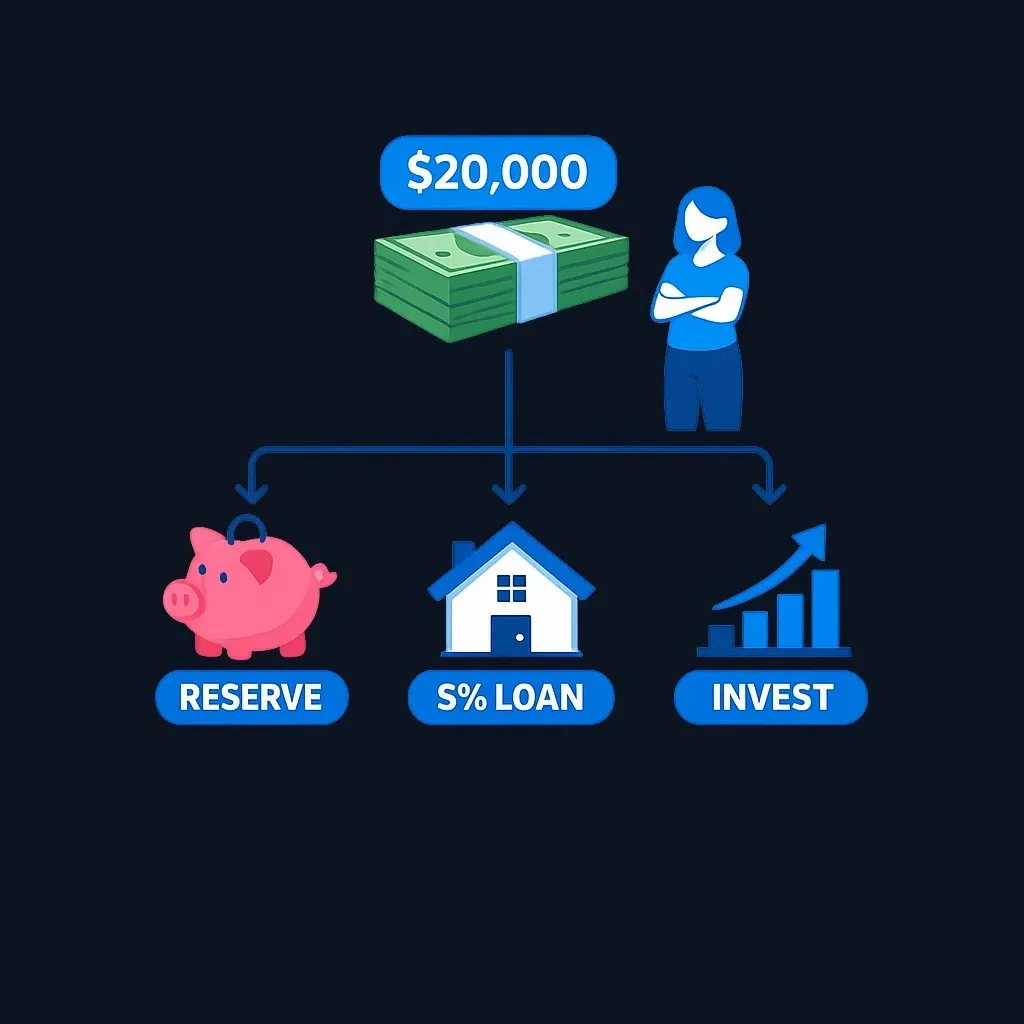
Keep these seven points written down for your own comparison; they make your eventual choice defensible and repeatable.
Decision framework
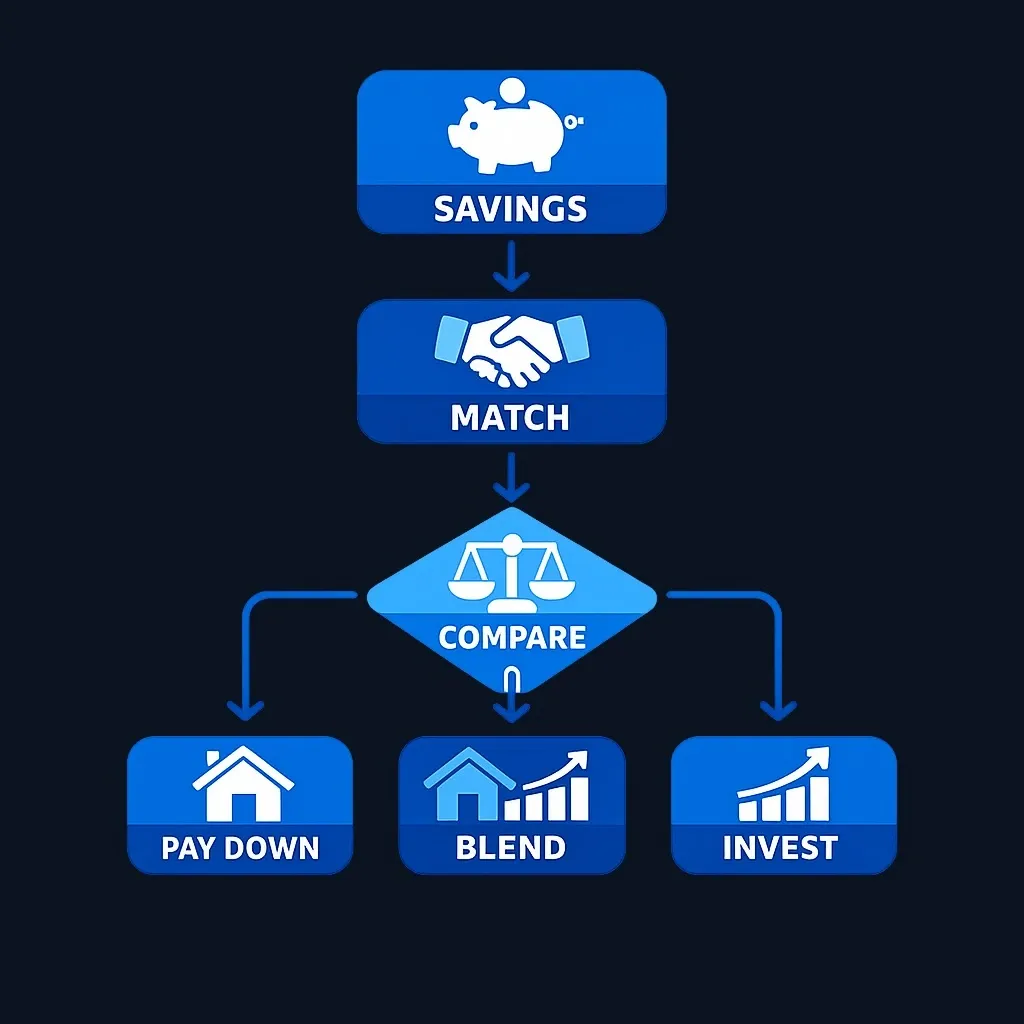
Use this 4‑step framework to turn choices into numbers and a clear decision.
Step 1 — Gather inputs
Write down:
- Your mortgage rate and remaining term.
- Any prepayment penalties or limits on extra principal.
- Your marginal tax environment (estimate).
- Expected after‑tax return you reasonably expect from your preferred investments and the horizon for those returns.
- Current emergency fund size and other high‑cost debt.
Note: “Expected return” should be a realistic, conservative estimate you can defend, not a wishful number.
Step 2 — Compare effective returns (simple test)
- Treat the mortgage rate as a starting estimate of contractual interest avoided through additional principal payments, then adjust for taxes, fees, liquidity, and the loan's actual prepayment terms.
- Compare those estimated interest savings with a range of plausible after-tax investment outcomes, including losses—not with a single assumed return.
- If expected after‑tax investment return > mortgage rate (and you accept the investment risk), investing often makes sense. If mortgage rate > expected after‑tax investment return, paying down mortgage often makes sense.
This is a heuristic, not an absolute rule; consider liquidity, taxes, and emotional preference next.
Step 3 — Adjust for risk, liquidity and taxes
- Risk: If you require certainty (e.g., low risk tolerance, near retirement), value the guaranteed savings more highly.
- Liquidity: If you need access to cash for job risk, health, or funding education, prioritize liquidity (investments or cash) over permanent payoff.
- Taxes: If mortgage interest is partially deductible in your situation, reduce the effective mortgage rate accordingly when you compare. If investments will be in tax‑protected accounts (retirement accounts), the tax drag may be lower.
Create a simple “decision score” by assigning weights to return, risk tolerance, and liquidity (for example: return 50%, risk 30%, liquidity 20%) and score payoff vs investing. This produces a single, auditable recommendation you can revisit.
Step 4 — Make a hybrid plan if you’re unsure
You do not have to pick one exclusive path. Common hybrid moves:
- Split excess cash between extra principal and investments (for example, 50/50).
- Funnel employer matching retirement contributions first, then decide between mortgage vs additional investing. Employer matches are effectively instant returns that are hard to beat.
- Use a time‑boxed experiment: commit extra funds to investing for 12–24 months; if results are below expectations, switch more cash to mortgage payoff.
Checklist: before you act, ensure you have
- Adequate emergency savings (3–6 months or more if income unstable).
- No high‑interest consumer debt outstanding.
- Understanding of prepayment penalties or mortgage recast rules.
- A realistic expected return for your investment approach.
Decision table — qualitative comparison
| Criterion | Pay Off Mortgage | Invest |
|---|---|---|
| Guaranteed financial benefit | High (interest saved) | None (returns uncertain) |
| Risk profile | Lower portfolio volatility | Higher volatility; return uncertainty |
| Liquidity | Low (funds trapped in home equity) | Higher (varies by account) |
| Tax complexity | Potentially simpler; check interest deductibility | Potential for favorable tax‑advantaged accounts or capital gains treatment |
| Emotional/psychological effect | Debt relief, reduced stress | Potential wealth growth, future flexibility |
Use the table to map your priorities: if you value lower risk and emotional security, payoff leans positive; if you prioritize long‑term wealth accumulation and can tolerate volatility, investing leans positive.
The Emotional Aspect: Debt vs. Freedom
Financial math matters, but emotions often decide behavior. Recognize these common psychological effects and how to handle them.
The peace of mind from being debt‑free
Owning your home outright reduces fixed obligations and can reduce stress from job loss or income shocks. For many people, that psychological gain improves overall well‑being and sleep quality. If being debt‑free will change your spending, savings discipline, or career choices in ways you value, it’s a legitimate factor.
Tip: quantify the emotional benefit by asking how much you would pay to eliminate that stress. If you’d willingly pay a 1% lower investment return to be stress‑free, include that in your decision score.
The excitement and patience needed for investing
Investing requires tolerating periods of drawdown. If watching portfolio swings leads you to sell at the wrong time, projected higher returns can be illusory in practice. If you know you’ll keep contributing through downturns and hold long term, investing’s volatility is less important.
Behavioral hybrid: a pragmatic plan
If emotions push you strongly one way, use a hybrid that secures emotional benefits while preserving upside:
- Make a meaningful one‑time principal payment to gain psychological relief, then direct future extra cash into investments.
- Set a target date to reassess (e.g., after two years of steady savings).
Recognize common mistakes:
- Over‑reacting to short‑term market movements by switching from investing to payoff impulsively.
- Ignoring liquidity needs and then being forced to borrow at high cost later.
- Using the “sunk cost” fallacy — don’t let past mortgage payments determine future rational allocations.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Tax implications of each option
Tax rules can tip the balance but rarely swing the whole decision by themselves. Because laws and personal circumstances differ, treat tax effects as adjustable parameters in your framework.
What to consider:
- Mortgage interest deductibility: this depends on local tax rules and personal filing details; it reduces the effective mortgage rate for those who itemize and qualify.
- Tax treatment of investment gains: retirement accounts (tax‑deferred or tax‑advantaged) change after‑tax return calculations; taxable accounts face capital gains and dividend taxes in many jurisdictions.
- Contributions to tax‑advantaged retirement accounts may be limited by income or employer plan rules; prioritize employer match when available — it’s an immediate return on your money.
Checklist before relying on tax effects:
- Confirm mortgage interest rules in your tax jurisdiction with a tax professional.
- Model after‑tax returns for your expected investments (account type matters).
- Consider that tax laws can change; don’t rely solely on a temporary advantage.
Case studies: real‑life scenarios (hypothetical examples)
These examples are hypothetical and meant to illustrate how to use the decision framework. They do not predict future results.
Case A — Risk‑averse homeowner near retirement (Hypothetical)
Profile: Age 58, mortgage balance smallish relative to retirement assets, no high‑interest debt, modest emergency fund.
Decision path:
- Prioritize mortgage payoff for guaranteed reduction in monthly outflow and peace of mind.
- Keep retirement contributions up to any employer match first.
- After mortgage is paid, redirect freed cash flow to diversified retirement investments.
Why this fits: near retirement, preserving capital and reducing fixed expenses is often more valuable than chasing uncertain market returns.
Case B — Mid‑career saver with strong retirement goals (Hypothetical)
Profile: Age 40, steady income, mortgage rate moderate, no other high‑interest debt, employer match available, long time horizon for retirement.
Decision path:
- Review employer-matched retirement contributions first because an available match can materially change the comparison; verify eligibility, vesting, contribution limits, fees, and plan terms rather than describing the match as a guaranteed investment return.
- Split remaining extra cash: a substantial portion into long‑term investments, a portion to extra mortgage principal.
- Reassess yearly with the decision framework.
Why this fits: long horizon increases the chance that investment returns exceed the mortgage rate; balancing both addresses emotional and financial goals.
Case C — Young household, tight liquidity (Hypothetical)
Profile: Age 30, small emergency fund, variable income, anxious about cash flow.
Decision path:
- Build a robust emergency fund first.
- Pay down high‑interest debts.
- Once emergency fund is adequate, choose a conservative split toward mortgage and investing.
Why this fits: liquidity and buffer against income shocks are priority before longer‑term tradeoffs.
Worked example (how to run the numbers yourself — hypothetical math):
- List mortgage rate (e.g., M%), expected after‑tax investment return (e.g., R%), and monthly extra cash available.
- Calculate interest saved by extra principal over remaining loan term using an amortization tool or calculator.
- Project investment growth for the same contributions over your chosen horizon using compound return formula.
- Compare projected ending wealth and sensitivity to different returns (e.g., R ± 3 percentage points).
These steps let you see how sensitive the decision is to return assumptions and time horizon.
Tools and Calculators for decision making
You don’t need complex software to compare options — these tool types are sufficient.
- Mortgage amortization calculator: shows how extra principal changes interest paid and term remaining. Use it to quantify guaranteed savings.
- Investment return calculator / compound interest calculator: projects how regular contributions might grow at assumed annual rates.
- Break‑even calculator: solves for the investment return at which investing equals the mortgage payoff in net wealth at a target date.
- Cash‑flow planner or simple spreadsheet: compare monthly budgets, including reduced mortgage payments vs. investment contributions.
Where to start: build a two‑column spreadsheet. Column A models using extra cash for mortgage payoff; Column B models investing the same cash. Include emergency fund level, tax assumptions, and a conservative range of returns. For plain guidance on distinguishing saving and investing, see the government investor education resource on saving vs. investing (Investor.gov).
Practical tips for using tools:
- Run sensitivity checks (best‑case, expected, worst‑case investment returns).
- Include a realistic sequence of returns test if you’re near retirement (sequence risk matters).
- Update the model annually or after major life changes.
FAQ
Should I pay off my mortgage early?
Paying off a mortgage early guarantees interest savings and reduces monthly obligations, which many people value. Consider liquidity, alternative uses for the cash (high‑yield investments or paying high‑interest debt), and your emotional preference before deciding.
How do I calculate the ROI of paying off my mortgage versus investing?
Treat the mortgage rate as the effective guaranteed ROI of payoff. For investing, estimate the conservative after‑tax return you expect and compare the two. To be precise, calculate projected net wealth under each path using an amortization schedule for payoff and a compound interest projection for investing.
How do interest rates affect my decision?
A higher mortgage rate generally increases the contractual interest that an extra principal payment may avoid, which can make payoff more attractive relative to uncertain investment outcomes. A lower rate may shift the comparison toward investing for someone who has adequate liquidity and can tolerate loss, but neither direction is automatic; taxes, fees, loan terms, horizon, and risk capacity matter.
How can I balance investing for retirement while paying off my mortgage?
Common approaches: (1) prioritize employer‑matched retirement contributions, then split extra cash between investing and mortgage; (2) make a meaningful lump payment toward principal for psychological relief, then invest additional funds; (3) set a fixed percentage split (for example, 60% invest / 40% extra principal) and review annually.
Conclusion: Making your decision
There is no universal answer. Use the decision framework: quantify your mortgage rate and expected after‑tax investment return, confirm your liquidity and emergency fund, weigh tax considerations, and include emotional factors. If you remain uncertain, a hybrid plan (split contributions, time‑boxed experiments) preserves upside while reducing regret.
For a practical next step, run a mortgage amortization and an investment projection side by side in a spreadsheet, then score the results against liquidity, risk, taxes, time horizon, and peace of mind. Treat projected returns as assumptions rather than promises.
Sources and Further Verification
Financial LiteracyU.S. GuideFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
What is the 50/30/20 Rule and How to Implement It
If you search for "what is the 50 30 20 rule," it’s a simple budgeting guideline that divides after-tax (take-home) income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt reduction Consumer Financial Protection Bureau. Use it as a starting template, not…
Finelo Team
Financial Literacy
What is a Grace Period on a Credit Card?
A credit-card grace period is the time between the end of a billing cycle and the payment due date when new purchase balances may not accrue interest if you pay the statement balance in full by the due date. This is the standard definition used by the Consumer…
Finelo Team
Financial Literacy
A Complete Guide to Student Loan Cosigner Release
A cosigner release is a lender-offered process that removes a cosigner’s legal obligation from a private student loan once the primary borrower meets the lender’s conditions—typically a run of on-time payments and a credit check of the borrower alone CFPB. Check your loan documents and contact your servicer…
Finelo Team