Last editorial review: October 7, 2026
What is Cash Stuffing? A Practical Guide to Budgeting with Envelopes
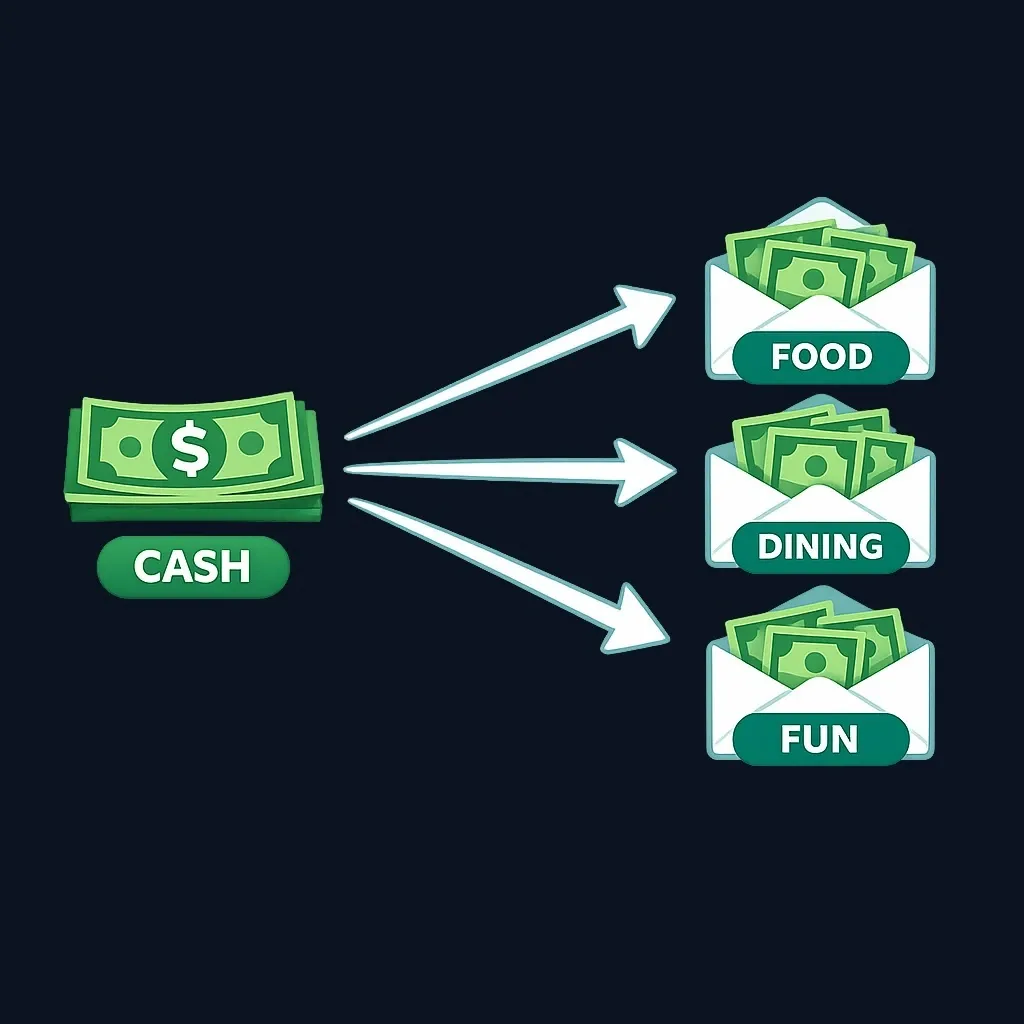
Cash stuffing (the envelope method) is a hands‑on budgeting technique where you allocate physical cash to labeled envelopes for each spending category and spend only what’s in each envelope. It helps make overspending visible and tangible and can be a useful tool if you handle cash well and…
7 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
Cash stuffing (the envelope method) is a hands‑on budgeting technique where you allocate physical cash to labeled envelopes for each spending category and spend only what’s in each envelope. It helps make overspending visible and tangible and can be a useful tool if you handle cash well and want strict category limits Consumer Financial Protection Bureau.
How Cash Stuffing Works
Cash stuffing is a simple cycle: plan, withdraw, allocate, spend, and refill. Here’s the core mechanics you’ll use each budgeting period.
Step-by-step process
- Plan your budget period (monthly, biweekly, or per pay run). Decide which categories you’ll fund with cash.
- Withdraw the total cash you’ll use for that period from your bank or ATM.
- Label envelopes for each category (groceries, dining out, transport, etc.). Optionally add a small note of the target amount or recordable balance inside.
- Put the allocated cash into each envelope and store them where you’ll access them for that category.
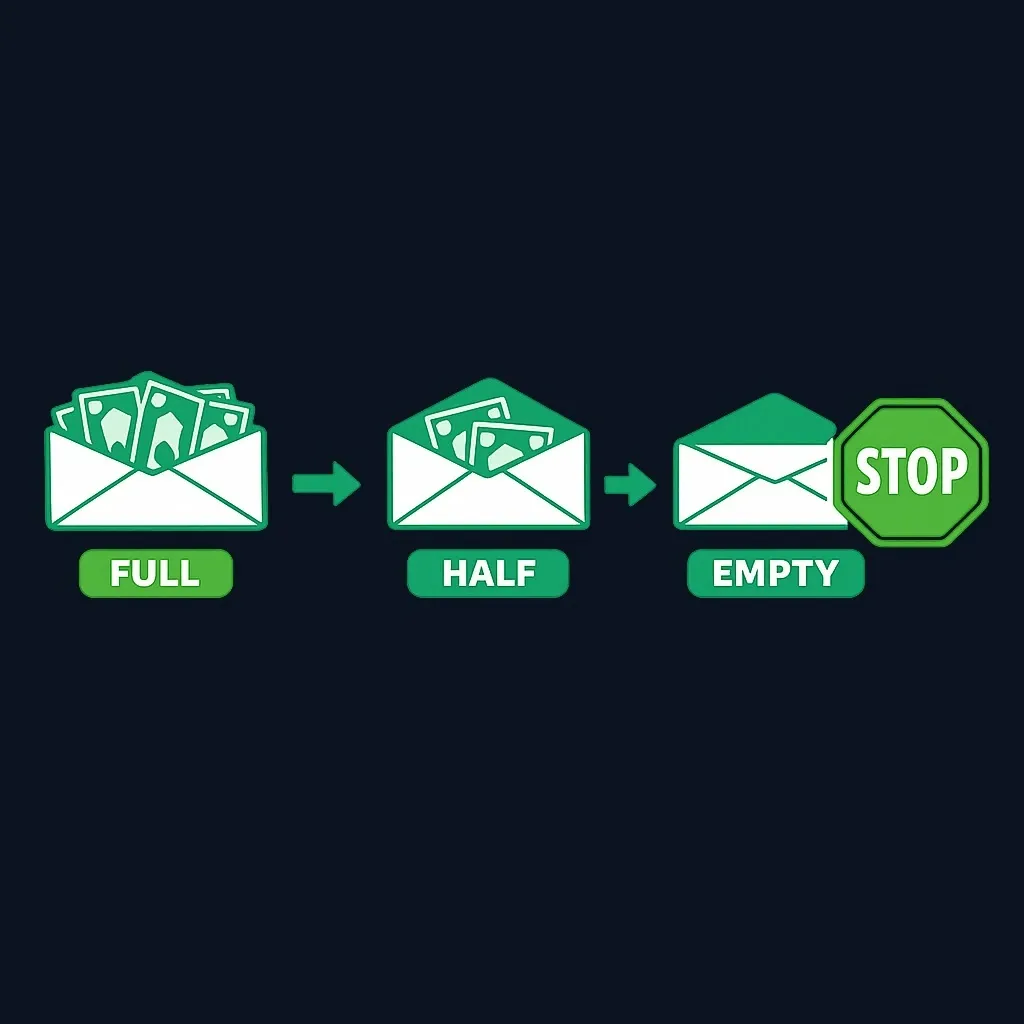
- When buying something, use only the cash from the matching envelope. When it’s empty, no more spending in that category until the next refill.
- At the end of the period, reconcile receipts and adjust allocations for the next cycle.
Quick checklist (use every cycle)
- Identify categories to fund with cash.
- Decide the budget period (monthly, biweekly).
- Withdraw cash once per period.
- Label and stuff envelopes.
- Track spending and adjust next cycle.
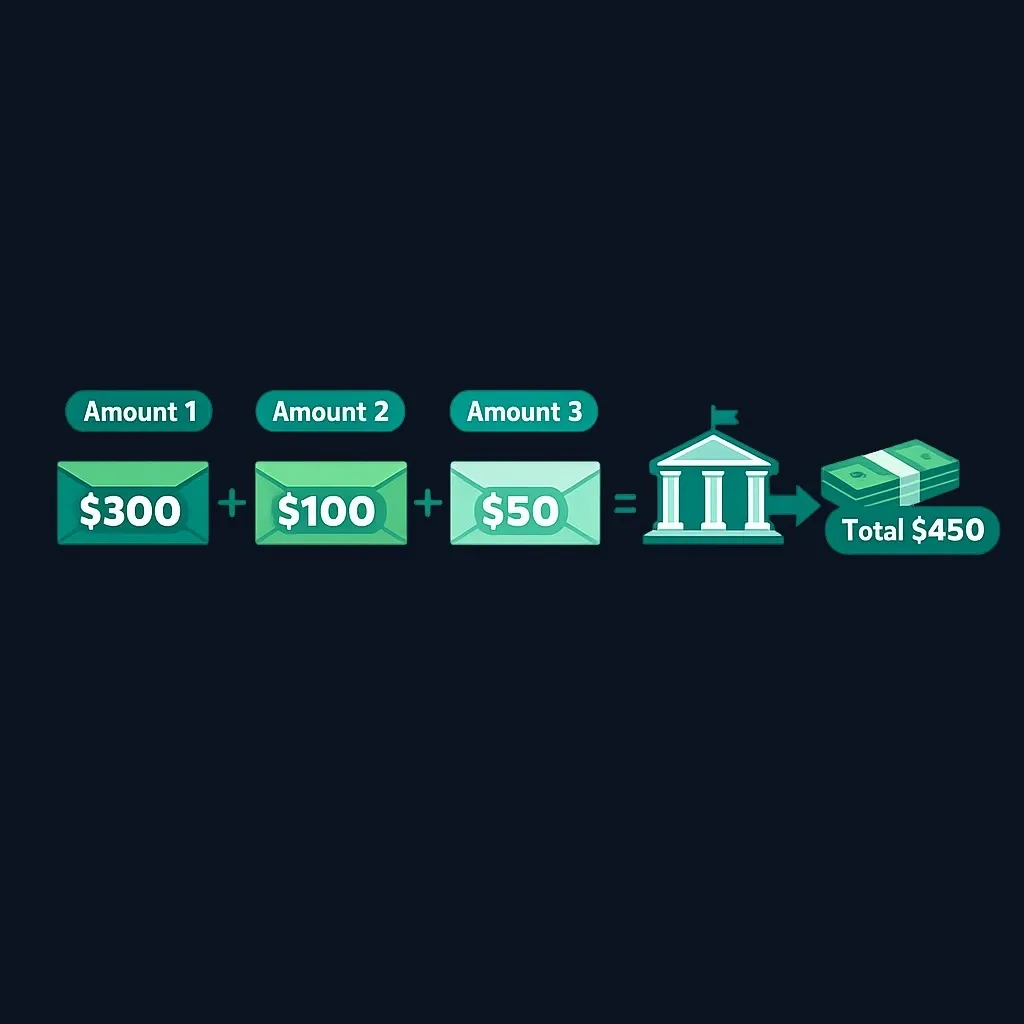
Compact table: What each envelope represents
| Envelope label | Purpose |
|---|---|
| Essentials | Recurring needs like groceries or transport |
| Discretionary | Dining out, entertainment, hobbies |
| Savings buffer | Emergency top‑up or irregular expenses |
| Bills (optional) | Small fixed payments you prefer to settle in cash |
Use that table as a working model — choose labels that reflect how you actually spend.
What to know before deciding
This section helps you weigh whether cash stuffing fits your goals, habits, and constraints. Read this before you commit.
Benefits
- Tangible limits: Physically seeing cash decrease makes spending decisions more deliberate and can reduce impulse buys. This behavioral effect is a key practical benefit.
- Simple to start: The method needs no apps or accounts; anyone who can withdraw cash can try it quickly.
- Good for targeted overspending: Many people use envelopes only for categories where they habitually overspend, keeping the rest of their money on cards or autopay. The envelope approach is a recognized budgeting tool for those who manage cash well Consumer Financial Protection Bureau.
Drawbacks and limits
- Security and loss risk: Carrying and storing cash increases the chance of loss or theft; consider where you keep envelopes and how much cash you carry.
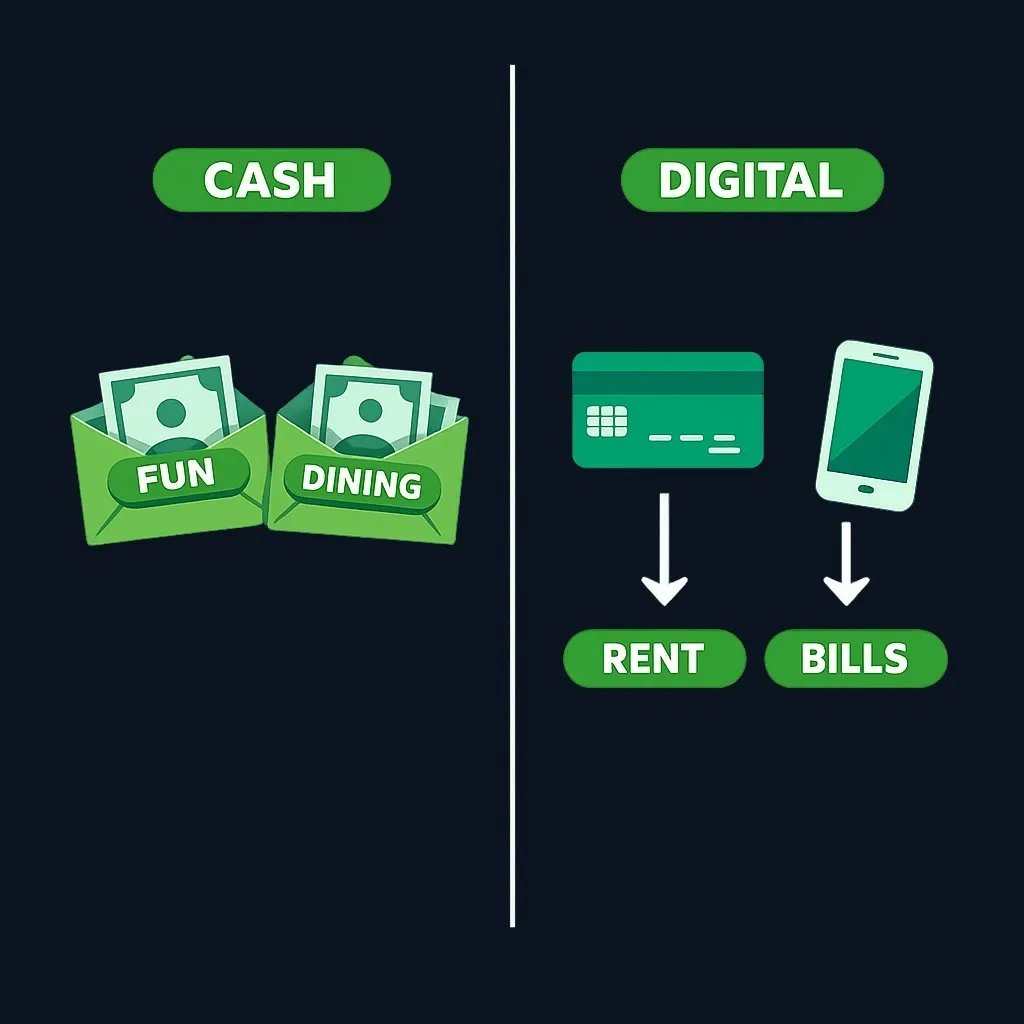
- Inflexible for some payments: Many bills and everyday services are best paid digitally. You may need a hybrid system (cash for discretionary categories, cards/autopay for fixed bills).
- Bank interaction and fees: Frequent withdrawals from certain accounts or ATMs can incur fees; check your bank’s policies.
- Doesn’t build credit or many digital records: If you rely on receipts and statements for recordkeeping, cash can make tracking slower unless you log expenses manually.
Getting Started with Cash Stuffing
A practical how‑to that helps you set up and run your first cycle without guesswork.
Decide scope and period
Pick two things first: which categories to fund with cash, and how often you’ll refill envelopes. Beginners often start with 3–6 envelopes (one for groceries, one for dining out, one for transit, etc.) and a monthly cycle. If you prefer smaller, more frequent resets, try a biweekly cycle aligned to paydays.
Set realistic categories and priorities
- Start with categories where you overspend. You don’t need an envelope for every expense type.
- Include a “buffer” envelope for irregular expenses (gifts, one‑off repairs). That prevents those costs from wrecking your essentials.
Track and adjust
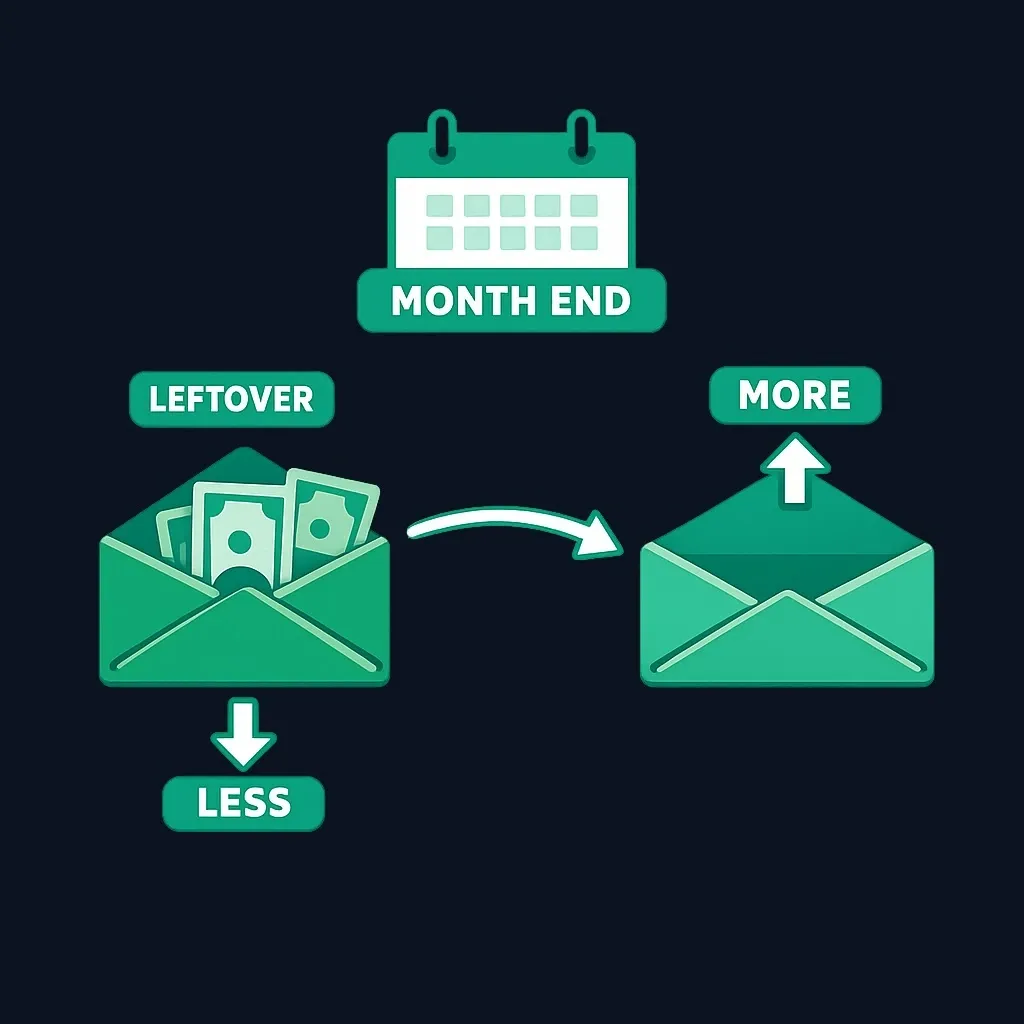
At the end of each period, count what’s left, total receipts, and note where you went over or under. Use that data to tweak envelope targets next period.
Practical example (structure only): imagine your variable spending is split into three envelopes: Essentials, Fun, and Buffer. If Essentials run out every month, move part of Fun into Essentials next cycle. Avoid changing targets mid‑cycle unless essential.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Tips for Effective Cash Stuffing
Small operational choices make the system sustainable. These tips come from common practice and behavioral principles.
Keep envelopes visible but secure
Store envelopes in a dedicated pouch, binder, or drawer. Visibility helps with discipline; a locked box or keeping large sums at home reduces theft risk.
Use receipts or a quick tracker
Either keep receipts in each envelope or use a single notebook or phone note to log expenses. Reconciling makes future allocations more accurate.
Hybrid approach: when cash meets cards
Many people use cash stuffing only for discretionary categories and keep a bank card for bills and subscriptions. This combines the behavioral benefits of envelopes with the convenience of digital payments.
Common mistakes and fixes
- Mistake: Using one envelope for too many purposes. Fix: Narrow categories; split “Fun” into “Dining” and “Entertainment” if those are distinct overspending areas.
- Mistake: Overcomplicating with dozens of envelopes. Fix: Consolidate to the few categories that influence your spending most.
- Mistake: No recordkeeping. Fix: Reconcile weekly for the first month to build accurate targets.
Decision framework
Use this quick checklist to decide whether to try cash stuffing and how to pilot it.
- Behavior fit: Do you respond to physical limits? If yes, cash stuffing can help.
- Spending pattern: Are impulse purchases concentrated in a few categories? If yes, use envelopes for those categories first.
- Safety and convenience: Are you comfortable carrying cash and making periodic ATM withdrawals? If no, consider a partial or digital alternative.
- Income predictability: If your income is steady, a per‑month envelope cycle is straightforward. If income is irregular, see the next FAQ for an adaptation framework.
How to pilot: Run a one‑month experiment with 3–5 envelopes. Track results and decide whether to expand, adjust, or stop. Focus on outcomes you can measure: lower overspend in targeted categories, clearer visibility, or simpler monthly reconciliation.
FAQ
What is cash stuffing?
Cash stuffing is a modern name for the envelope method: you withdraw cash, divide it into labeled envelopes, and spend only what’s in each envelope for that category Consumer Financial Protection Bureau.
How do I start cash stuffing?
Begin by choosing 3–6 categories where you overspend, decide on a refill period (monthly is common), withdraw the cash you intend to use, label envelopes, and log spends. Reconcile at period end and adjust allocations for the next cycle.
Can cash stuffing work for irregular income?
Yes. Prioritize funding essentials and build a buffer envelope first. After essentials are covered, allocate remaining cash to variable categories. Consider shorter cycles that align with when you receive paychecks so cash flow and envelopes stay synchronized.
Is cash stuffing safe?
Carrying cash has theft and loss risks. Keep only what you need for the period on your person, use a secure storage place at home, and avoid carrying large amounts. For safer convenience, use a hybrid model: envelopes for discretionary spending and digital payments for bills and recurring obligations.
Conclusion and Next Steps
Cash stuffing is a practical, low‑tech way to make spending visible and enforce category limits. If you want to test it, run a one‑month pilot with a few focused envelopes, track results, and refine targets. You can copy the categories and review questions in this article into a paper note or spreadsheet; no separate Finelo download is required.
Sources and Further Verification
Financial LiteracyU.S. GuideFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
What is the 50/30/20 Rule and How to Implement It
If you search for "what is the 50 30 20 rule," it’s a simple budgeting guideline that divides after-tax (take-home) income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt reduction Consumer Financial Protection Bureau. Use it as a starting template, not…
Finelo Team
Financial Literacy
What is a Grace Period on a Credit Card?
A credit-card grace period is the time between the end of a billing cycle and the payment due date when new purchase balances may not accrue interest if you pay the statement balance in full by the due date. This is the standard definition used by the Consumer…
Finelo Team
Financial Literacy
A Complete Guide to Student Loan Cosigner Release
A cosigner release is a lender-offered process that removes a cosigner’s legal obligation from a private student loan once the primary borrower meets the lender’s conditions—typically a run of on-time payments and a credit check of the borrower alone CFPB. Check your loan documents and contact your servicer…
Finelo Team