Last editorial review: October 7, 2026
How to Start Saving Money: A Comprehensive Guide
Start saving today by choosing one concrete goal, automating a small transfer timed to your payday, and keeping that money in a separate savings account. Pause or cancel one recurring cost and route that cash into the starter fund. Check progress after 30 days and increase transfers when…
7 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
Start saving today by choosing one concrete goal, automating a small transfer timed to your payday, and keeping that money in a separate savings account. Pause or cancel one recurring cost and route that cash into the starter fund. Check progress after 30 days and increase transfers when feasible.
Scope and verification
Finelo publishes educational content to help beginners build financial skills; treat this guide as learning material rather than personalized financial advice. For structured lessons and basic banking guidance, the FDIC’s Money Smart program offers free resources for people learning money management (FDIC Money Smart).
What to know before deciding
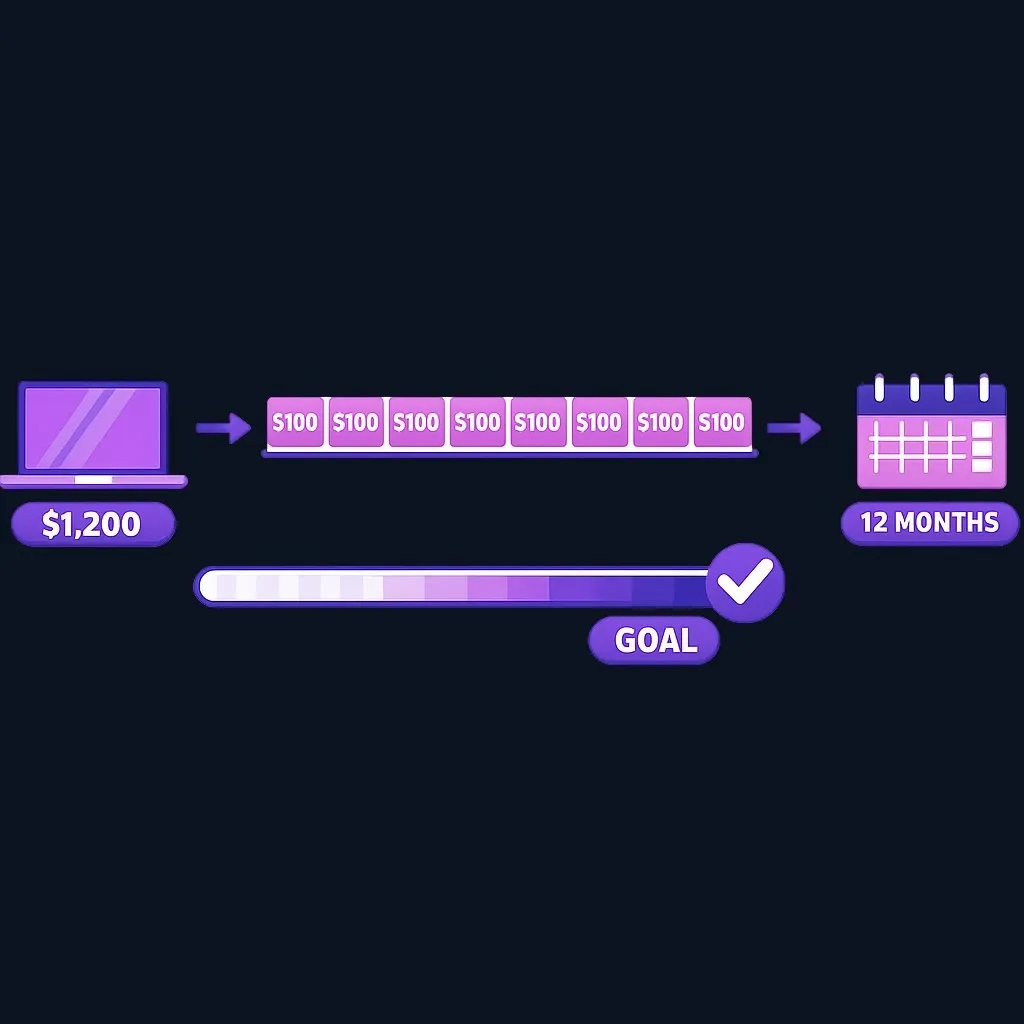
Saving gives options: it covers short shocks, funds planned purchases, and reduces reliance on credit. Before you act, decide which problem you’re solving — a small starter buffer, an upcoming expense, or long-term goals — because the right account and approach depend on the horizon.
Starter checklist (do these in the first week)
- Track every dollar in and out for 7 days to see where money flows.
- Open or designate a separate savings account so the starter fund is visible.
- Schedule an automatic transfer timed just after payday.
- Cancel or pause one small recurring cost and route that money to savings.
Concrete caveat: product names and account features vary by bank. Match access and safety to your timeline — don’t lock short-term money into accounts with long withdrawal penalties.
Understanding Your Financial Situation
Begin with a clear snapshot of income, regular obligations, and debt.
Step 1 — income and fixed costs: list take-home pay and unavoidable monthly bills (rent, utilities, insurance). Step 2 — variable spending: track one month of groceries, transport, and subscriptions to find average variable costs. Step 3 — debts and interest: record minimum monthly debt payments and their interest rates to prioritize high-cost borrowing.
Decision point: if high-interest debt forces frequent borrowing, allocating some cash to a small buffer can avoid expensive late fees while you pay debts faster. Use realistic figures; budgeting from wishful numbers breaks plans quickly.
Worked example (simple)
- Take-home pay: $3,000/month.
- Fixed bills: $1,700.
- Average variable: $600.
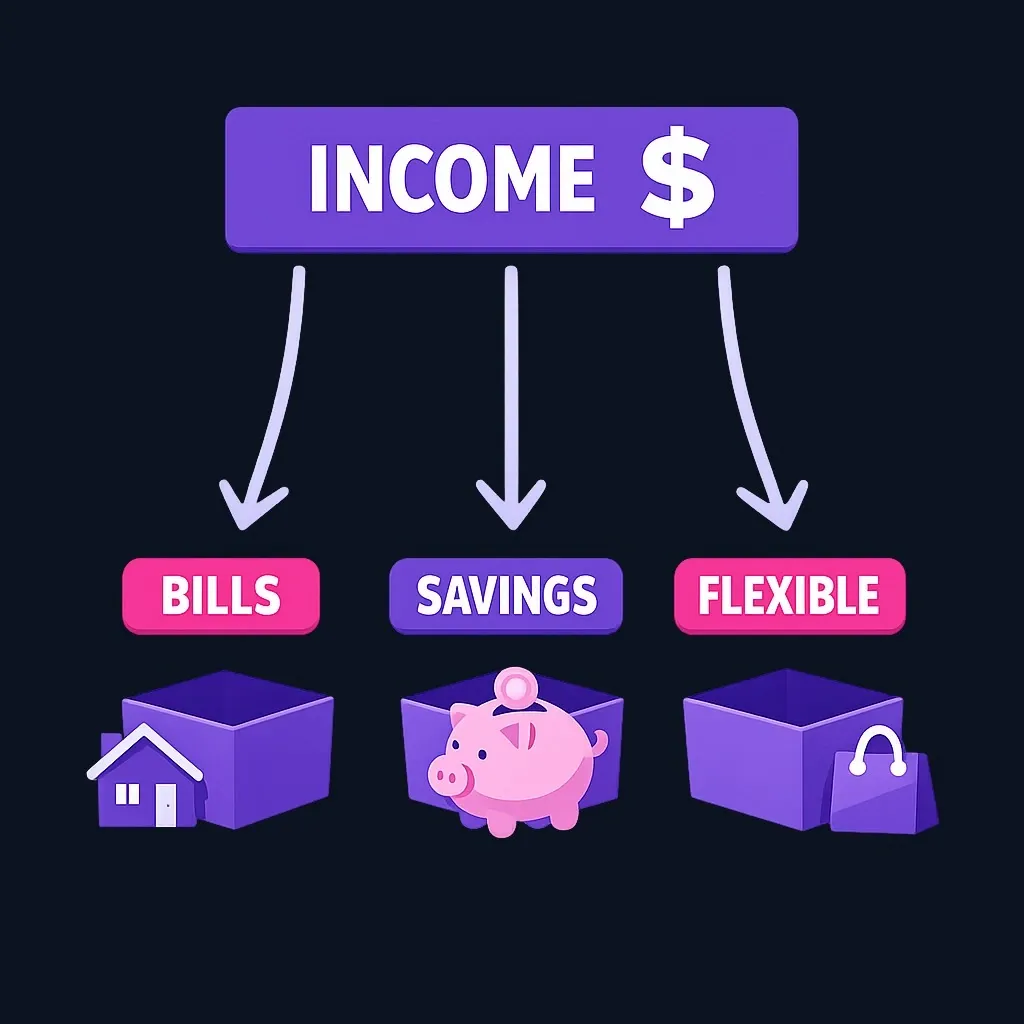
- Discretionary cash: $700. If you automate $150/month to savings, you keep momentum without straining daily needs.
Decision framework
Goal: choose where to start so actions match the problem you want to solve.
SMART goals quick guide
- Specific: name the purpose and dollar amount.
- Measurable: set a clear balance target and a date.
- Achievable: pick a cadence you can sustain.
- Relevant: align the goal to your priorities (safety, purchase, retirement).
- Time-bound: give it a realistic deadline.
Visual decision table (tradeoffs)
| Goal horizon | Example use | What matters most | Where to hold it |
|---|---|---|---|
| Short-term (days–months) | Starter fund, small purchase | Liquidity, immediate access | Regular savings / separate account |
| Medium-term (months–years) | Car down payment, big trip | Yield vs access | High-yield savings or short-term CDs |
| Long-term (years+) | Retirement, house down payment | Growth and tax treatment | Retirement or investment accounts |
Concrete example: if essential monthly bills total $2,000 and you want a 3-month buffer, target $6,000. Choose a cadence (weekly/biweekly/monthly) that reaches the target without creating persistent cash shortfalls.
Caveat: product details differ across banks. Verify limits and withdrawal terms before you lock money away.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Creating a Budget That Works
A practical budget is simple, repeatable, and protects savings.
Step-by-step process
- Record take-home pay and list fixed monthly bills first.
- Track variable spending for one month to compute reasonable averages.
- Subtract fixed + average variable from take-home to find discretionary cash.
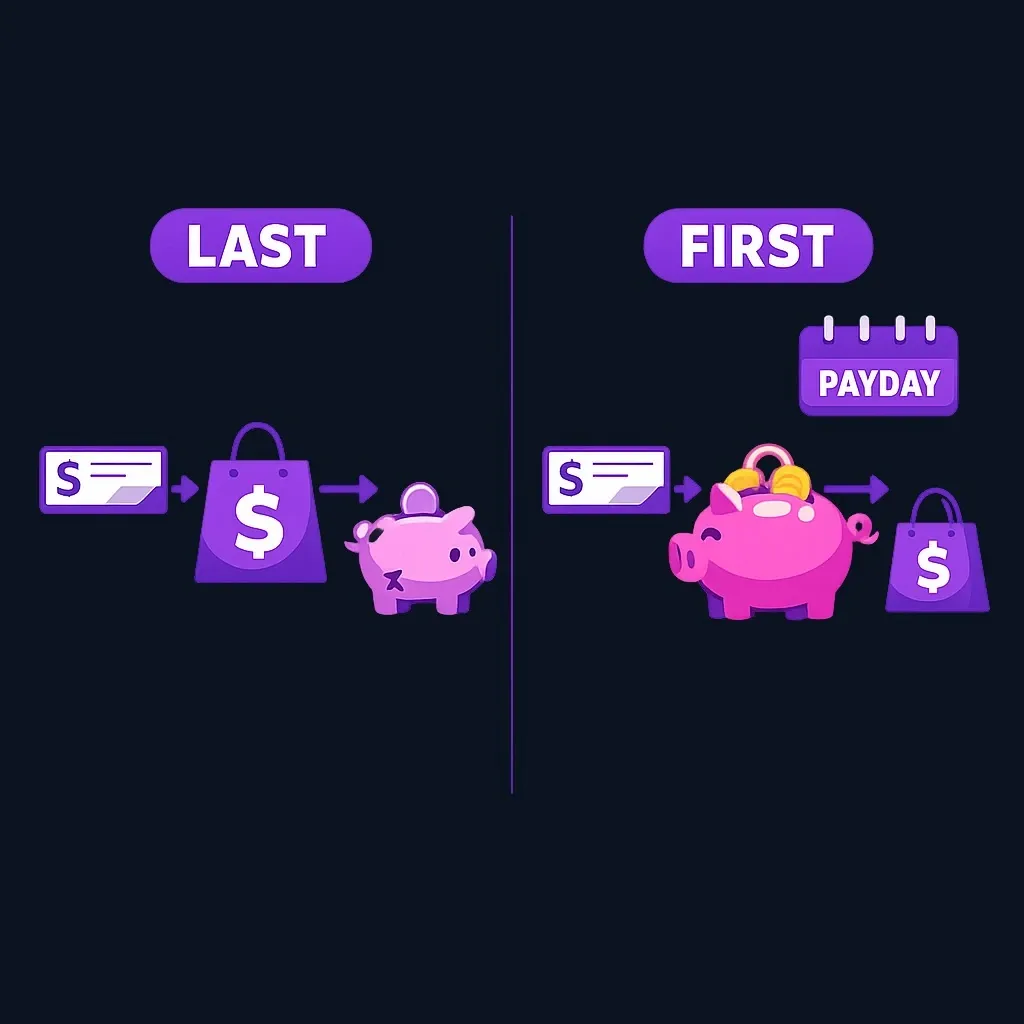
- Pay savings first by automating a transfer — treat it like a bill.
- Keep a small flexible buffer to avoid frequent overdrafts.
Worked example (allocation)
- Discretionary cash: $700.
- Automate $150/month to emergency starter fund.
- Allow $300 for discretionary fun.
- Use $250 for extra debt payments or other goals.
Decision point: if an automated transfer would leave you short, lower the amount and identify one recurring cost to cancel or renegotiate.
Practical rule: use a 30-day waiting rule for nonessential purchases over a set threshold to reduce impulse buys.
Strategies for Effective Saving
Automate first; optimize repeatedly.
Automate savings
- Schedule an automatic transfer for the day after payday so savings never compete with bills.
- When income rises, consider increasing the transfer by a small percentage.
Choosing tools and features
- Prefer apps that show goal progress, schedule recurring transfers, and offer clear category labeling.
- If privacy or data portability matters, confirm export or manual categorization features before committing.
Cutting expenses (practical wins)
- Audit subscriptions and pause ones you rarely use.
- Compare service plans and ask providers about lower-cost options or promotions.
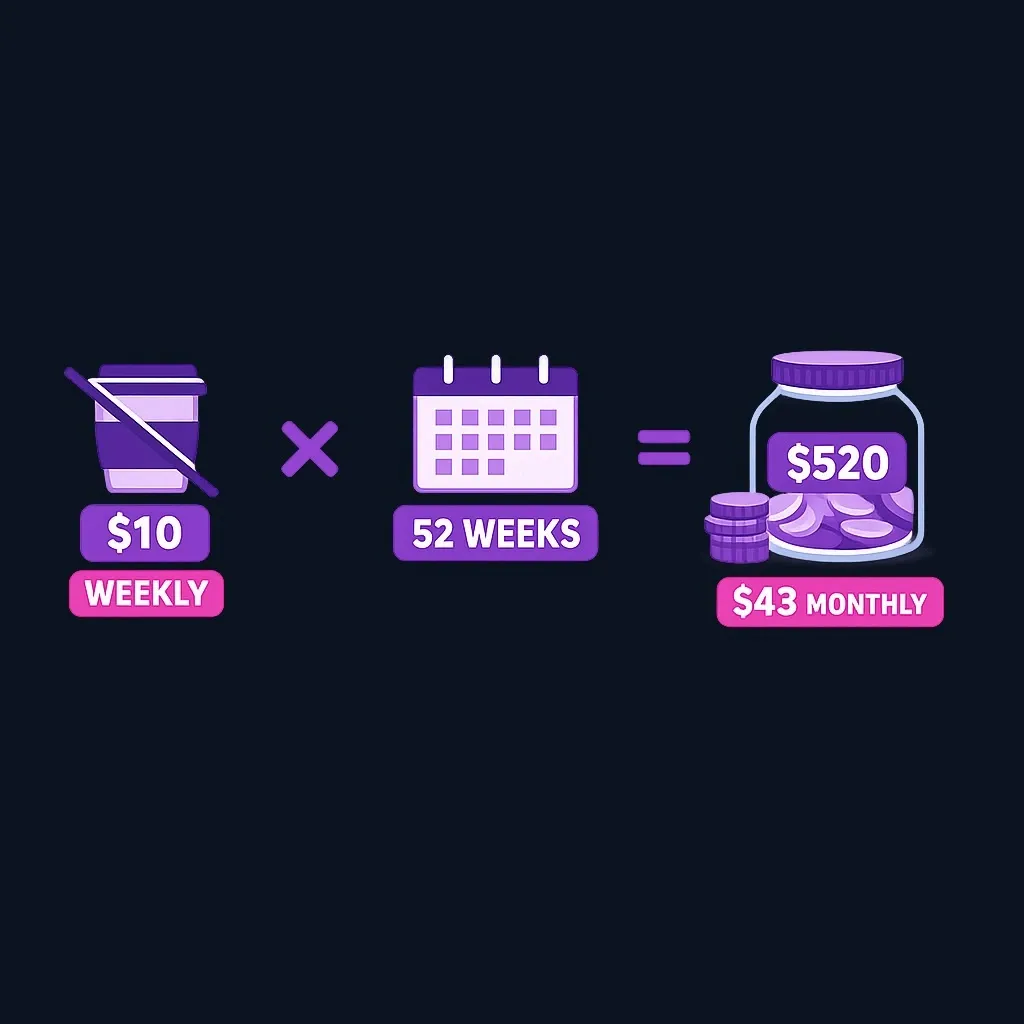
- Shift one discretionary line (e.g., weekly coffee out) directly into savings.
Simple negotiation script
- “I’m reviewing my plan and comparing options. Are there any promotions or lower-cost plans you can offer?” Small monthly savings compound over time.
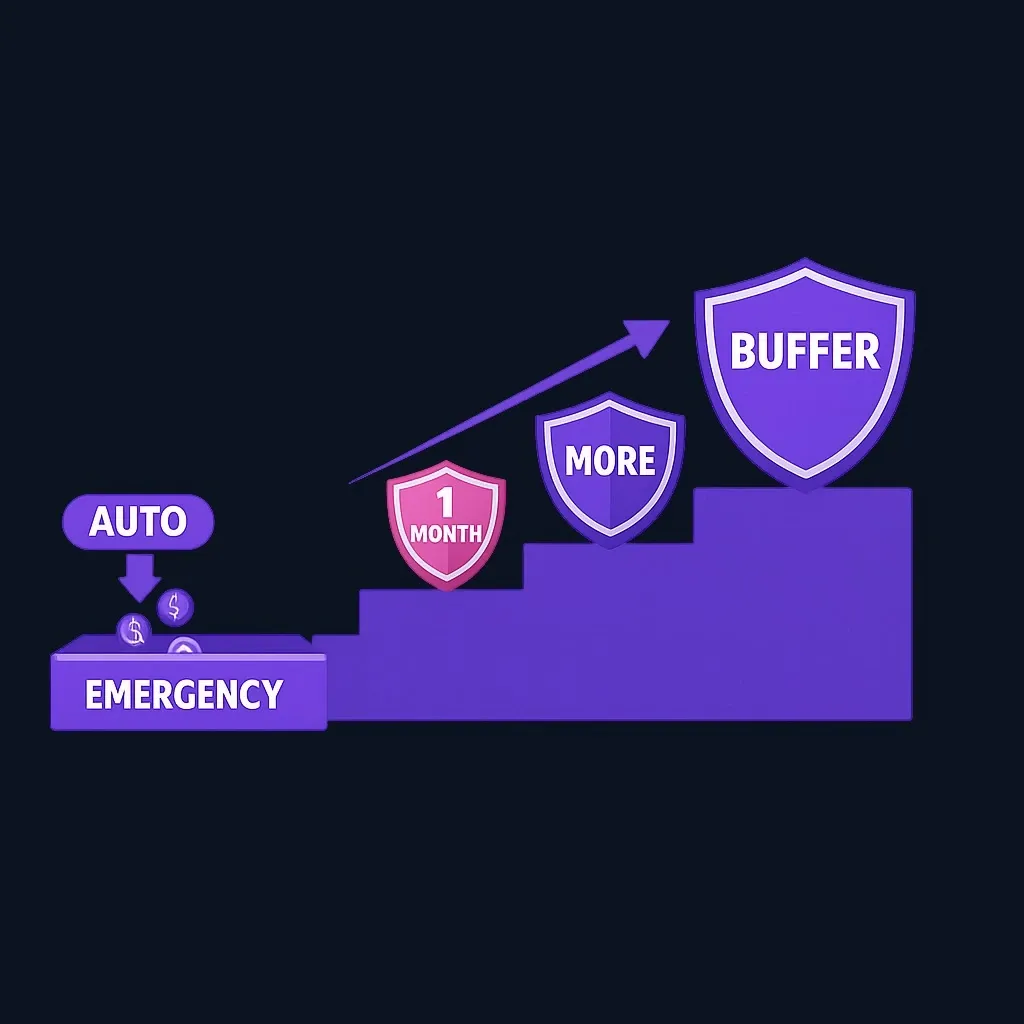
Building an emergency fund (integrated steps)
- Keep the fund in a separate, easily accessible savings account to avoid accidental spending.
- Start with a modest “starter” target you can reach quickly, then scale the goal over time.
- Automate a fixed contribution and add a portion of raises or windfalls to accelerate growth.
Resource: structured lessons on basic money skills are available in the FDIC’s Money Smart program (FDIC Money Smart). Use such resources for guided practice and worksheets.
Tracking and adjusting
- Review balances and scheduled transfers weekly.
- Mark milestones (first $500 saved) to reinforce behavior.
- If you miss two transfers in a row, reassess the amount and immediate needs.
Common Mistakes to Avoid When Saving Money
- Saving only leftover cash. Fix: automate transfers so saving is a planned expense.
- Keeping all goals in one account. Fix: label buckets or use separate accounts to prevent goal bleed.
- Chasing high returns with short-term money. Fix: match safety and liquidity to the time horizon.
- Letting unused subscriptions accumulate. Fix: audit subscriptions quarterly and cancel or pause.
- Setting vague goals. Fix: write a dollar amount and a date.
Quick recovery checklist for inconsistent savers
- Reduce the automated transfer to a sustainable amount.
- Pause a nonessential subscription and redirect that money to savings.
- Run a one-month no-new-purchases challenge to reset impulse habits.
Conclusion (next step) Take one concrete step today: track every transaction for seven days, pick one recurring cost to pause, and set a small automatic transfer timed to your next payday. Revisit the plan in 30 days and increase the transfer when you can.
FAQ
What are some effective ways to start saving money?
Start with one automatic transfer to a separate savings account, track spending for a week, and cancel or pause one recurring cost. These three actions free cash, build habit, and make progress visible.
How can I create a budget that works for me?
Record take-home pay, list fixed bills, estimate average variable costs, and treat savings as the first allocation. Keep the budget simple and adjust it monthly based on real spending.
What should I do if I can't save money consistently?
Lower the transfer to an amount you can sustain, automate it, and free up cash by pausing or cancelling one regular expense. Reassess after 30 days and increase savings gradually.
How much should I have in my emergency fund?
Base the target on your essential monthly expenses and the number of months of those costs you want covered. Calculate essentials first, then multiply by the months that fit your job stability and access to credit.
Use the steps above as a self-contained checklist: choose one small target, automate a realistic amount, review the first month, and adjust only after comparing the plan with actual cash flow.
Sources and Further Verification
Financial LiteracyU.S. GuideFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
What is the 50/30/20 Rule and How to Implement It
If you search for "what is the 50 30 20 rule," it’s a simple budgeting guideline that divides after-tax (take-home) income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt reduction Consumer Financial Protection Bureau. Use it as a starting template, not…
Finelo Team
Financial Literacy
What is a Grace Period on a Credit Card?
A credit-card grace period is the time between the end of a billing cycle and the payment due date when new purchase balances may not accrue interest if you pay the statement balance in full by the due date. This is the standard definition used by the Consumer…
Finelo Team
Financial Literacy
A Complete Guide to Student Loan Cosigner Release
A cosigner release is a lender-offered process that removes a cosigner’s legal obligation from a private student loan once the primary borrower meets the lender’s conditions—typically a run of on-time payments and a credit check of the borrower alone CFPB. Check your loan documents and contact your servicer…
Finelo Team