Last editorial review: October 7, 2026
How to Stop Impulse Buying: Practical Strategies for Better Spending Habits
Impulse buying is a sudden decision to purchase something without considering its impact on your money or goals; it’s often driven by emotion rather than reason Chase. To stop it: identify your triggers, use delay tactics (like waiting 48 hours), adopt a clear budget, and use real‑time spending…
7 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
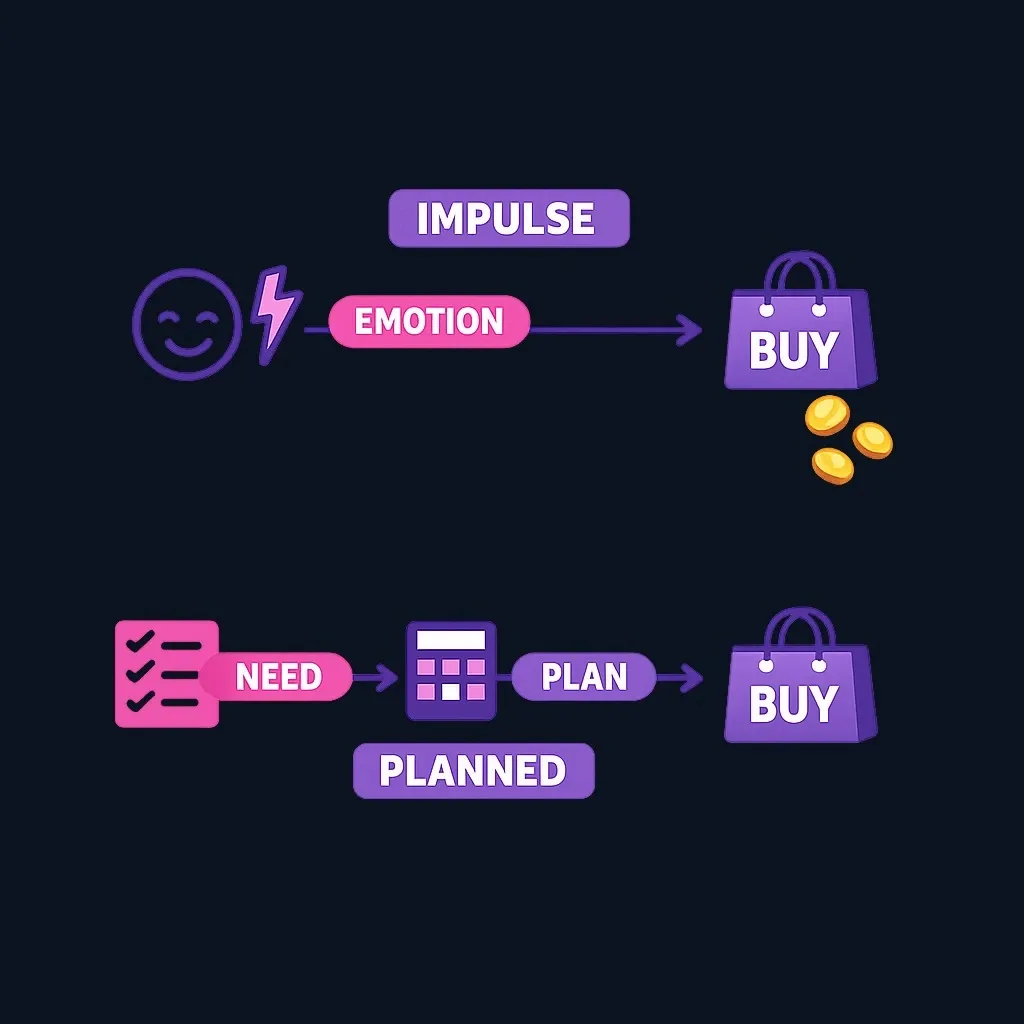
Impulse buying is a sudden decision to purchase something without considering its impact on your money or goals; it’s often driven by emotion rather than reason Chase. To stop it: identify your triggers, use delay tactics (like waiting 48 hours), adopt a clear budget, and use real‑time spending feedback tools to check progress CFPB. Example: before hitting “buy,” pause, ask “does this fit my budget?” and set a 48‑hour reminder.
What to know before deciding
Impulse buying is a behavioral pattern, not a moral failing. Chase defines it as a quick choice made without considering financial goals and notes it’s rooted more in emotion than reason Chase. Knowing that makes strategies about structure and friction more effective than willpower alone.
Example: Maria felt compelled to buy clothes after a rough day. Understanding that her purchases followed stress helped her replace shopping with a short walk and a capped weekly treat.
Decision framework
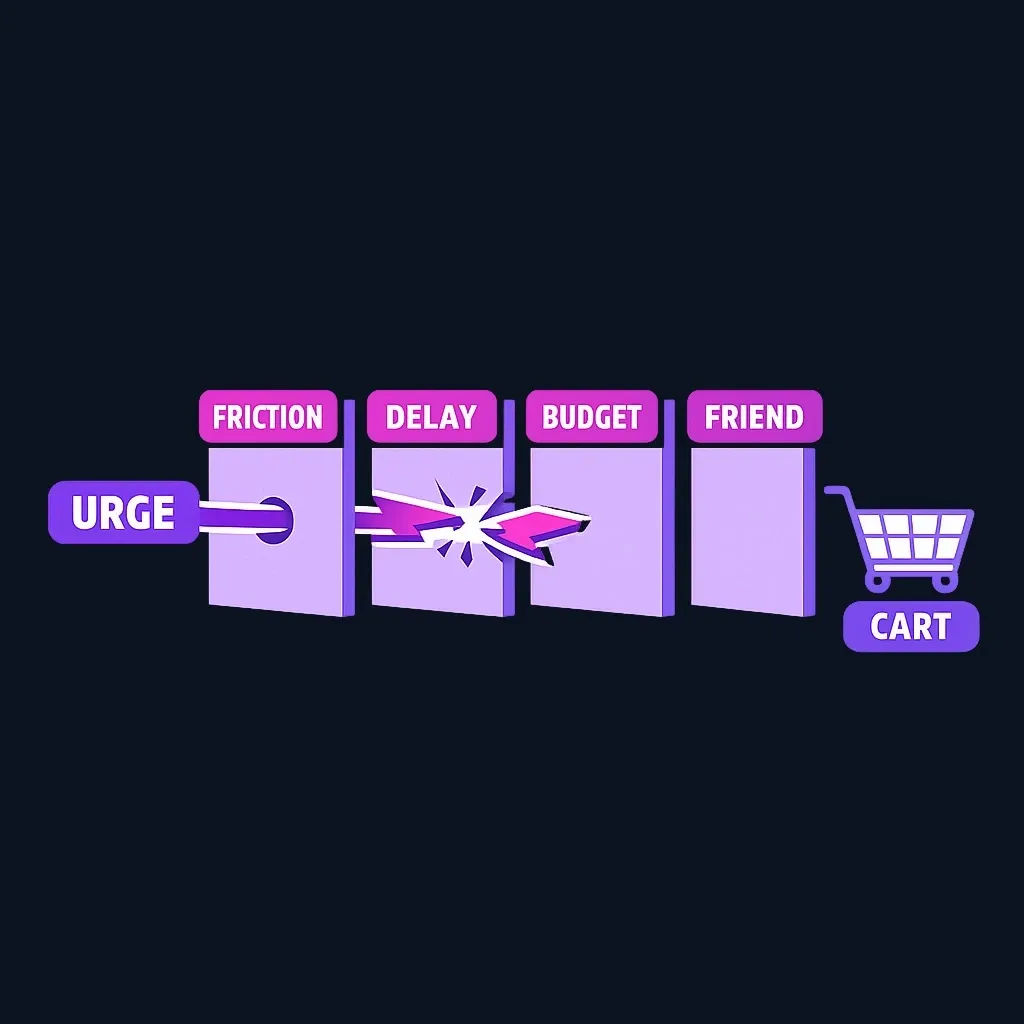
Use a compact decision framework to choose tactics that match your situation: (1) diagnose your trigger, (2) add friction to buying, (3) set rules and guardrails, and (4) monitor progress. Below are practical steps and concrete examples for each stage.
Identifying your impulse buying triggers
Goal: recognize patterns so you can prevent urges before they start.
- How to track triggers: keep a short “impulse log” for two weeks noting time, mood, channel (in‑store, social, email), and what you bought or almost bought.
- Common triggers: stress, boredom, scarcity messaging (limited-time offers), social comparison, and targeted ads. Chase recommends being attentive to the situations where you tend to impulse buy so you can spot the urge earlier Chase.
- Quick test: after an unplanned purchase, ask (a) Did I plan this? (b) Will it help my goals? (c) Would I still buy it tomorrow? The answers reveal whether the action was impulsive.
Example: An impulse log reveals that most impulse buys happen late at night after scrolling social apps — a clear intervention point.
Checklist: trigger indicators
- Time of day
- Emotional state
- Platform or store
- Type of product
- Marketing cue (sale, scarcity)
Practical Strategies to Stop Impulse Buying
Goal: give actionable techniques you can start today.
Use a layered approach — combine low friction (lists, budgets) with added friction (delays, payment controls).
- Use lists and rules: shop only with a prewritten list and one “fun” allowance per period. Example: a $30 weekly “treat fund.”
- Add payment friction: remove stored card data from shopping apps, log out of marketplaces, or use a secondary debit card with limited funds.
- Set automatic guards: freeze a credit card in a small wallet, or set app notifications to require approval before a purchase.
- Replace habit loops: when the urge hits, swap the action with a 10‑minute alternative (walk, call a friend, 10 deep breaths).
- Use spending feedback tools: consumers report that real‑time spending feedback can help curb impulse purchases and make budgeting easier CFPB.
Example: Jason deleted one-click checkouts and started logging potential purchases in a “maybe” note for 48 hours; his unplanned spend dropped.
Quick checklist (copyable)
- Carry a shopping list
- Unsave cards from apps
- Set one discretionary allowance
- Use spending alerts or financial apps
- Have a 10‑minute distraction ready
The 48-Hour Rule: A Delay Tactic
Goal: explain the rule and how to use it to break impulsive buying loops.
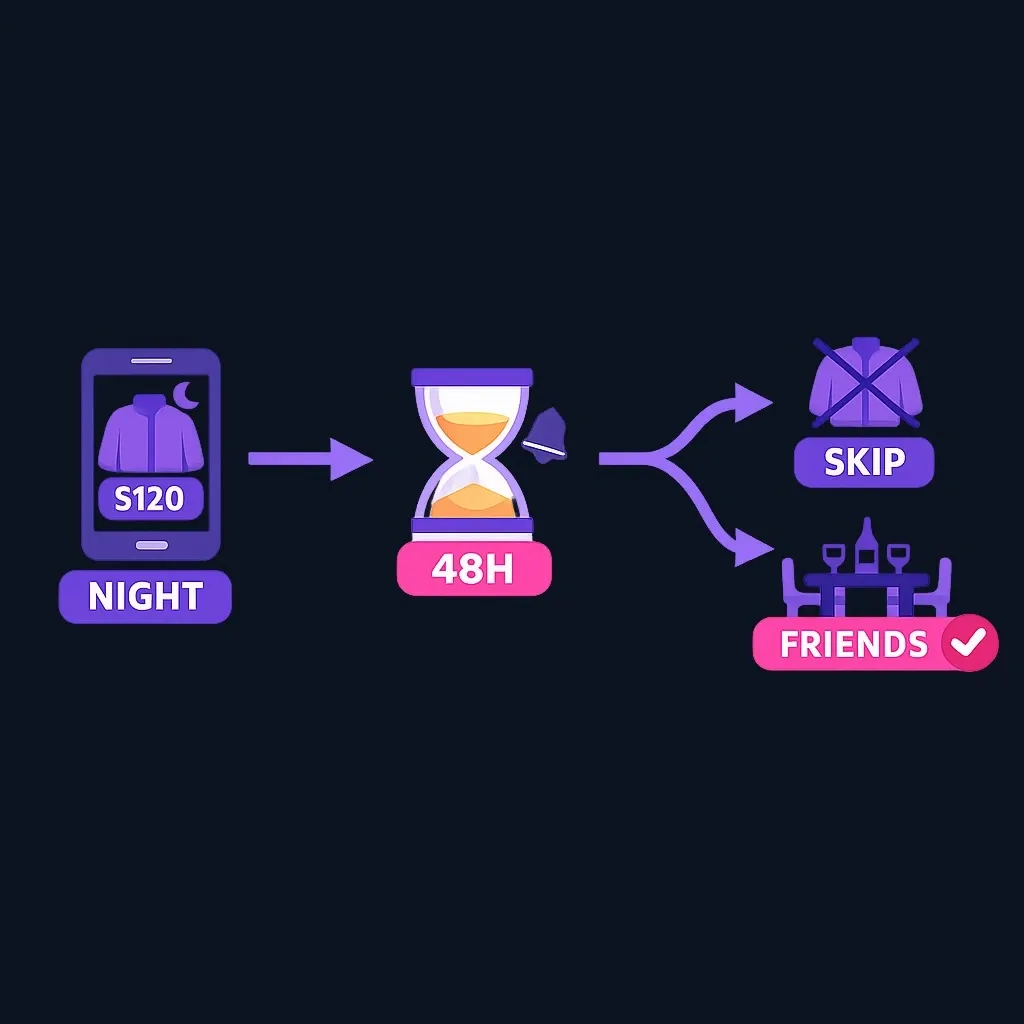
What it is: a simple waiting rule — don’t buy nonessential items for at least 48 hours. Use a calendar or reminder to enforce it. The delay separates a momentary desire from a considered decision; Chase and practical financial guides list delay tactics as effective behavior changes for impulse control Chase.
How to make it practical:
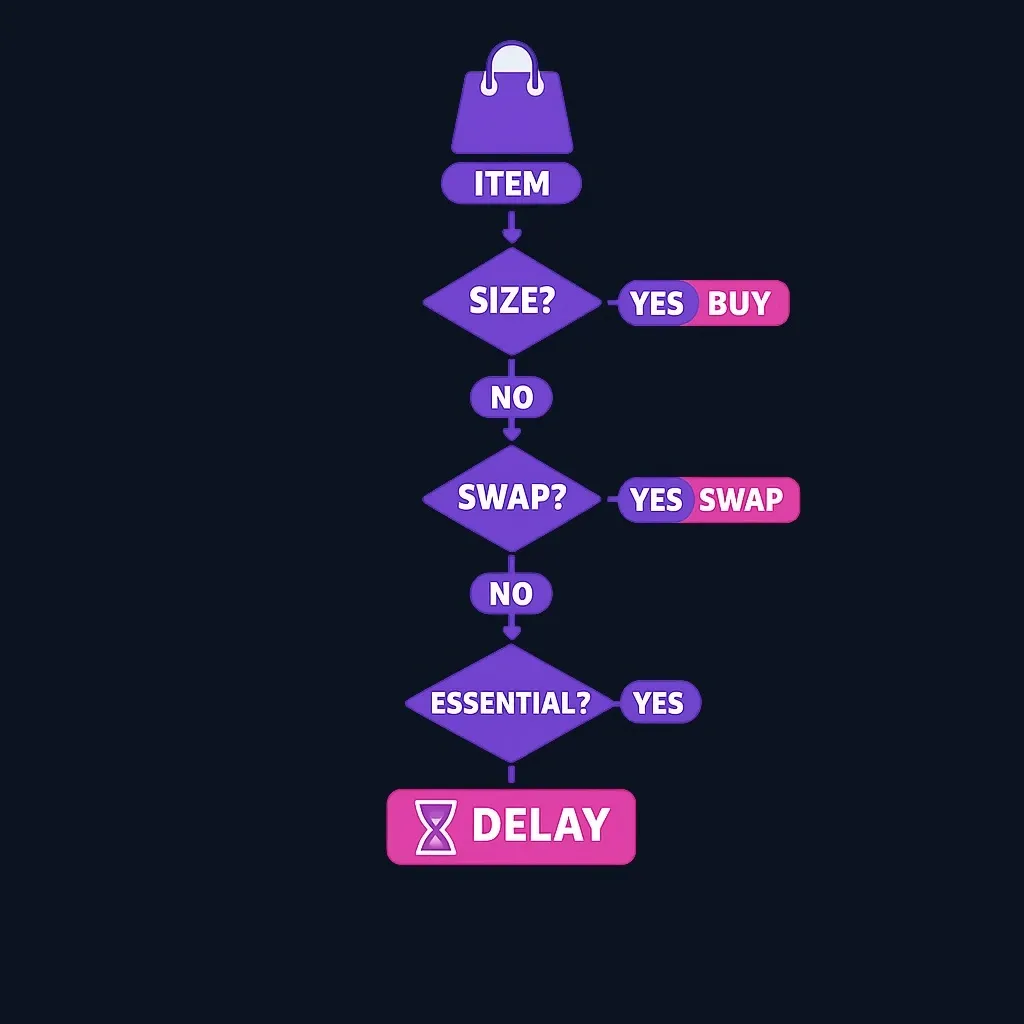
- Label purchases: “essential” or “nonessential.” Only essentials skip the delay.
- Use tools: set a 48‑hour calendar reminder or add an item to a “maybe” list app.
- Reevaluate after 48 hours: if you still want it and it fits your budget, consider buying; if not, delete the item.
Worked example: You see a gadget for $80. Add it to a “maybe” note. After 48 hours you realize you haven’t thought about it; you remove it and save $80.
Tip: For small frequent temptations (coffee, snacks), use shorter but consistent delay rules (e.g., 24 hours or “pause and count to 10”) to build habit discipline.
Creating a Budget: Your Financial Blueprint
Goal: practical budgeting steps that reduce the room for impulse buys.
Why budgeting helps: a clear budget defines what’s available for discretionary spending, turning vague limits into concrete allowances. That reduces “decision friction” at the point of sale.
Steps to build a simple, enforceable budget:
- Track last 30 days of spending to spot patterns.
- List fixed expenses and savings goals first.
- Allocate a discretionary category (weekly or monthly). Treat that as the limit for impulse-prone purchases.
- Automate savings and bill payments so discretionary money is explicit and accounted for.
Tools and monitoring: use bank alerts or budgeting apps to show remaining discretionary balances in real time — consumers say these tools can make it easier to stay within budget CFPB.
Decision rule example: If an item pushes you over your monthly discretionary allocation, don’t buy it now; move it to a future month’s list or the 48‑hour hold.
Practical example: Leah set a $200 monthly discretionary limit and a $20 weekly treat budget; seeing the remaining balance in her app stopped several unplanned buys.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Case Studies: Success Stories of Overcoming Impulse Buying
Goal: show realistic scenarios and what worked.
Case study A — Composite: “After pay‑day splurges”
- Problem: Sam would overspend the weekend after payday on dining and gadgets.
- Interventions: Sam implemented a $150 weekly discretionary cap, deleted saved cards from shopping apps, and used a 48‑hour “maybe” list.
- Outcome: Over three months, Sam redirected the surplus into an emergency fund and reduced late‑month stress.
Case study B — Composite: “Emotional spending at night”
- Problem: Priya shopped after stressful workdays and felt buyer’s remorse.
- Interventions: she tracked triggers for two weeks, substituted a 10‑minute breathing app, and set an “offline” rule after 9 p.m.
- Hypothetical outcome to track: Priya would compare the number and dollar value of unplanned purchases before and after the experiment, plus record whether regret or stress changed. The example illustrates a measurement method; it does not claim a typical or guaranteed result.
Each case is illustrative — adapt the tactics that match your triggers and lifestyle.
FAQ
What is impulse buying?
Impulse buying is a sudden decision to purchase without considering long‑term goals; it’s largely emotional rather than rational Chase.
How can I identify my impulse buying triggers?
Track purchases for two weeks noting time, mood, and channel. Patterns (late night, social media, stress) reveal your triggers. Chase recommends being attentive to situations where you tend to impulse buy so you can resist urges earlier Chase.
What strategies can I use to stop impulse buying?
Combine diagnosis (logs) with friction (remove saved payment methods), rules (48‑hour wait, discretionary budget), and monitoring (spending alerts or apps). Real‑time feedback tools can help keep you within budget CFPB.
Is it normal to make impulse purchases?
Yes. Occasional impulsive purchases are common and often driven by emotion, environment, or marketing. The goal is to reduce frequency and financial harm by changing environments and habits.
Conclusion: Taking Control of Your Spending Habits
Stopping impulse buying is about creating structure around decisions, not eliminating treats forever. Start with three small moves: track triggers for two weeks, set a discretionary budget, and use a 48‑hour rule for nonessentials. Add real‑time spending feedback (alerts or apps) to see progress; consumers find these tools helpful for staying within budget CFPB. Example next step: try a two‑week impulse log and one friction tweak (remove saved cards) and reassess results.
If you want a ready checklist to print and use this week, download Finelo’s free “Impulse Buying Action Plan” (no cost, practical steps you can start tonight).
Sources and Further Verification
Financial LiteracyU.S. GuideFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
What is the 50/30/20 Rule and How to Implement It
If you search for "what is the 50 30 20 rule," it’s a simple budgeting guideline that divides after-tax (take-home) income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt reduction Consumer Financial Protection Bureau. Use it as a starting template, not…
Finelo Team
Financial Literacy
What is a Grace Period on a Credit Card?
A credit-card grace period is the time between the end of a billing cycle and the payment due date when new purchase balances may not accrue interest if you pay the statement balance in full by the due date. This is the standard definition used by the Consumer…
Finelo Team
Financial Literacy
A Complete Guide to Student Loan Cosigner Release
A cosigner release is a lender-offered process that removes a cosigner’s legal obligation from a private student loan once the primary borrower meets the lender’s conditions—typically a run of on-time payments and a credit check of the borrower alone CFPB. Check your loan documents and contact your servicer…
Finelo Team