Last editorial review: October 7, 2026
How to Stop Living Paycheck to Paycheck: A Comprehensive Guide
Stop living paycheck to paycheck by (1) tracking every dollar, (2) creating a budget that forces saving, (3) starting a small emergency fund, (4) trimming or negotiating recurring costs, and (5) boosting income until you no longer need credit to cover unexpected bills. Even very small savings can…
8 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
U.S. scope: This article discusses U.S. institutions, financial products, tax rules, and dollar examples unless stated otherwise. Rules and product terms may change; verify current official guidance for your situation.
Educational note: This article is for educational purposes only and does not constitute financial, investment, legal, or tax advice. Finelo does not recommend any security, strategy, platform, or transaction. Investing and trading involve risk, including possible loss of principal. Verify current rules, fees, product terms, and suitability with official sources or a qualified professional.
Quick answer
Stop living paycheck to paycheck by (1) tracking every dollar, (2) creating a budget that forces saving, (3) starting a small emergency fund, (4) trimming or negotiating recurring costs, and (5) boosting income until you no longer need credit to cover unexpected bills. Even very small savings can increase financial security and make the cycle easier to break CFPB guide.
What to know before deciding
Before you act, two simple realities matter: mindset and measurement.
- Mindset: Change is gradual. Quick fixes (a single sale or one extra shift) help, but sustainable freedom comes from repeated small wins and clear priorities. Expect setbacks and plan for them.
- Measurement: You cannot fix what you don’t track. Knowing exact cash flow—when pay arrives, what bills are due, and which expenses are variable—lets you make targeted decisions.
Common causes of the cycle
- Pay timing mismatches (rent due before payday), thin or zero savings, high fixed costs relative to income, unmanaged debt, and irregular income. Recognize which apply to you so you can choose the right levers.
Who this guide helps
- Beginners who need clear steps and practical tools to move from living pay period to pay period toward predictable months and a safety buffer.
Decision point (quick caveat)
- If you face urgent bills or utilities at risk, prioritize immediate stopgaps (ask for a short-term payment plan, delay discretionary purchases). Use the decision framework below to choose next steps.
Decision framework
Use this 3-step framework to decide what to do first. Prioritize actions that (A) free the most cash quickly, (B) reduce future volatility, and (C) cost the least effort for long-term gain.
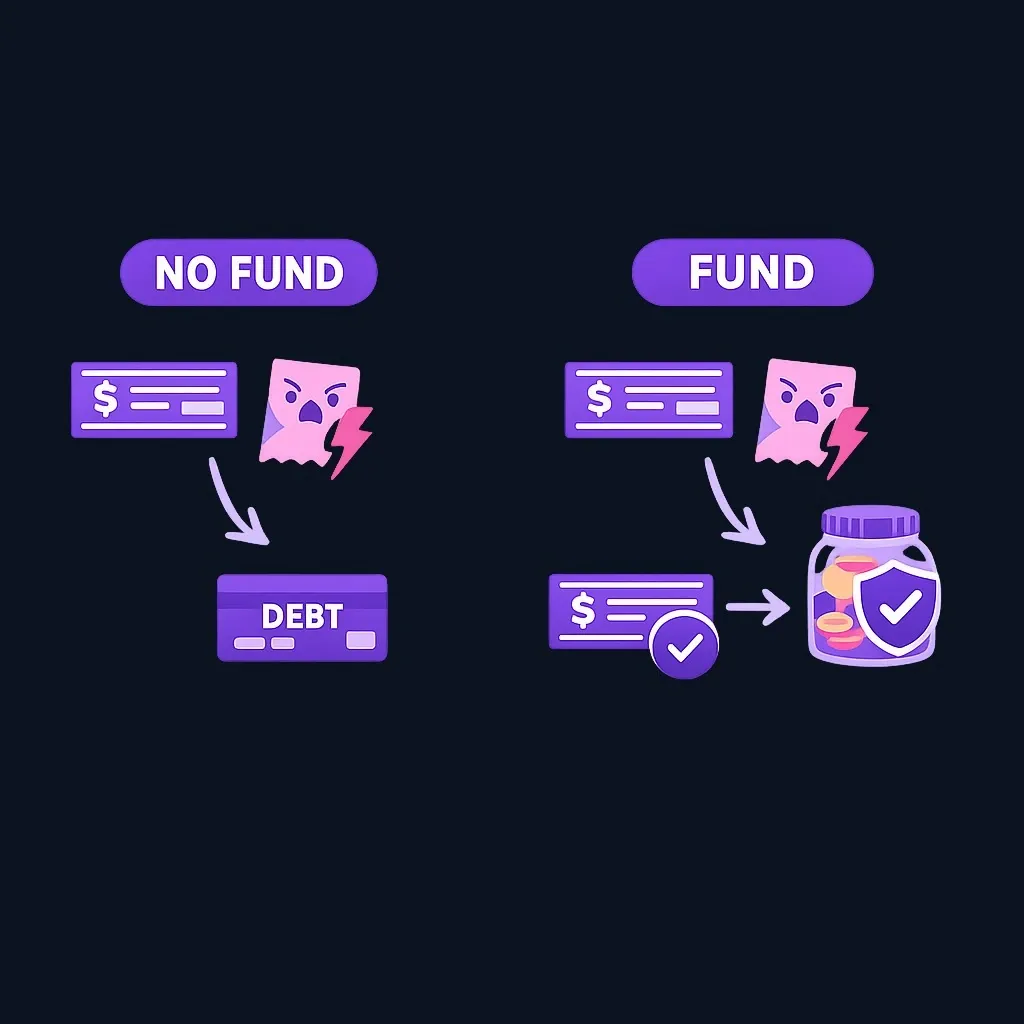
Table: Simple tradeoff view
| Action | Speed (how fast you’ll see cash) | Effort | Purpose |
|---|---|---|---|
| Re-time payments (move due dates) | Fast | Low | Avoid short-term shortfalls |
| Cut discretionary spending | Fast | Low–Medium | Free immediate cash |
| Negotiate recurring bills | Medium | Medium | Lower fixed costs long-term |
| Start a side income | Medium | High | Increase net cash flow |
| Build emergency fund | Slow | Low | Reduce future borrowing/hardship |
How to use it
- If you can free cash this month, stop using credit to cover essentials.
- If you have low or no savings, prioritize any action that builds a small buffer. The Consumer Financial Protection Bureau notes that even a small amount set aside provides meaningful security for people living paycheck to paycheck CFPB guide.
- Combine speed and sustainability: trim a repeatable monthly cost and use the freed cash to seed savings.
Quick checklist (first 14 days)
- List all income streams and dates.
- Track every expense for two pay periods.
- Move one recurring payment date if it prevents an overdraft.
- Pause one nonessential subscription.
- Deposit any windfalls to a separate savings bucket.
Creating a Realistic Budget
A budget is a plan that assigns every dollar a job. When done properly it prevents surprises and makes saving possible.
Step-by-step budget (actionable)
- Tally net income (after taxes and deductions). Include irregular income averaged monthly.
- Record fixed essentials: rent/mortgage, utilities, insurance, minimum debt payments, groceries, transportation.
- List variable and discretionary expenses: dining out, subscriptions, entertainment. Track actuals for two pay cycles.
- Subtract essentials + variable from income. If negative or zero, act on the Decision framework to free cash. If positive, assign the surplus to short-term savings, debt reduction, or a prioritized goal.
Zero-based budgeting (use when possible)
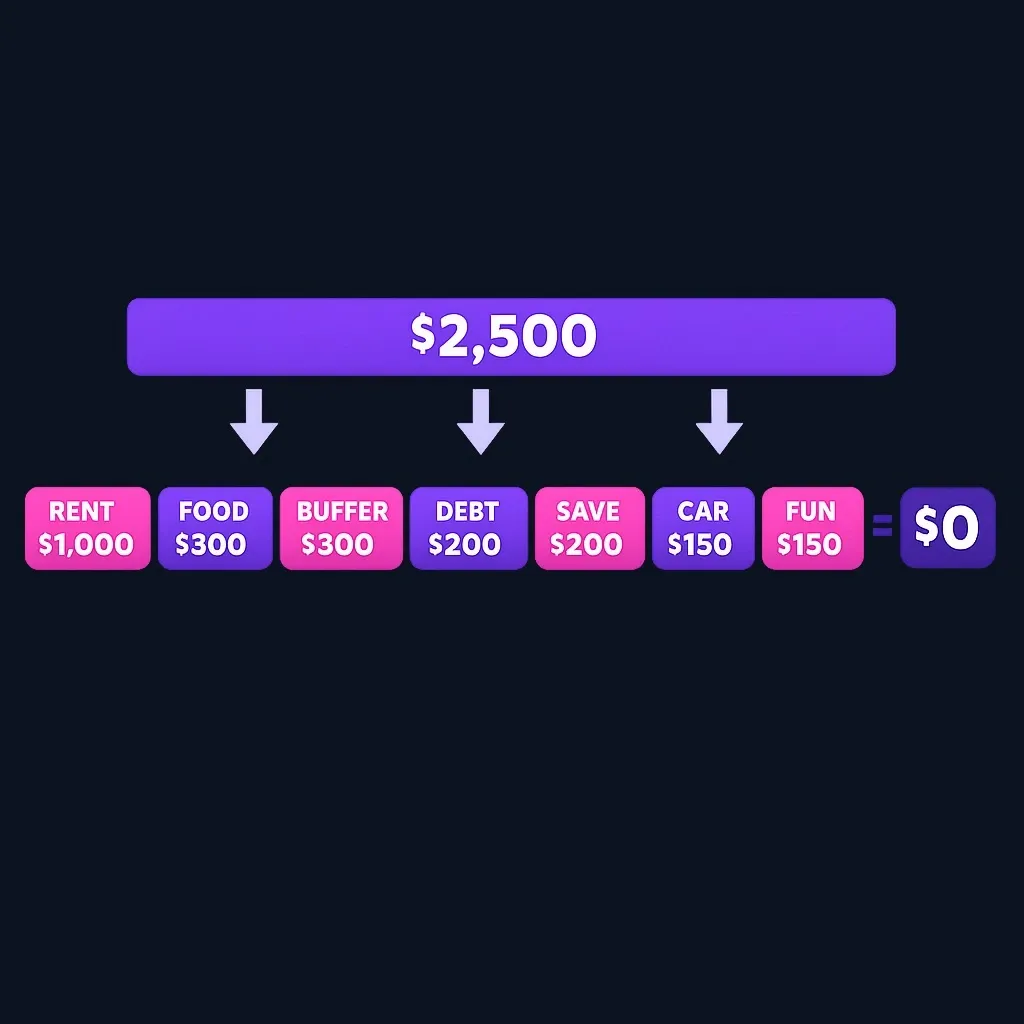
- Assign every dollar on paper until income minus planned spending equals zero. This forces intentional use of cash and is particularly effective when living paycheck to paycheck because it eliminates “mystery money” leaks.
Worked example (monthly)
- Net income: $3,000 (hypothetical). Essentials: $2,200. Discretionary: $300. Guaranteed surplus: $500 → allocate $200 to emergency savings, $200 to high-priority debt, $100 to buffer/irregular expenses. This is an illustration of prioritization, not advice.
Tools and features to look for in a budgeting app
- Automatic transaction categorization, customizable categories, simple recurring budget rules, and the ability to create separate “buckets” or sub-accounts for savings. Choose a tool that matches your comfort level: spreadsheet-based control or automated syncing for minimal maintenance.
H3: Maintaining discipline inside the budget
- Automate: move small amounts to savings the day after payday.
- Micro-goals: celebrate a 30-day streak of saving any amount.
- Monthly review: reconcile budgets with real transactions and adjust categories.
Common mistakes and fixes
- Mistake: Underestimating variable bills (groceries, fuel). Fix: inflate budgeted amounts by 10–20% until you stabilize.
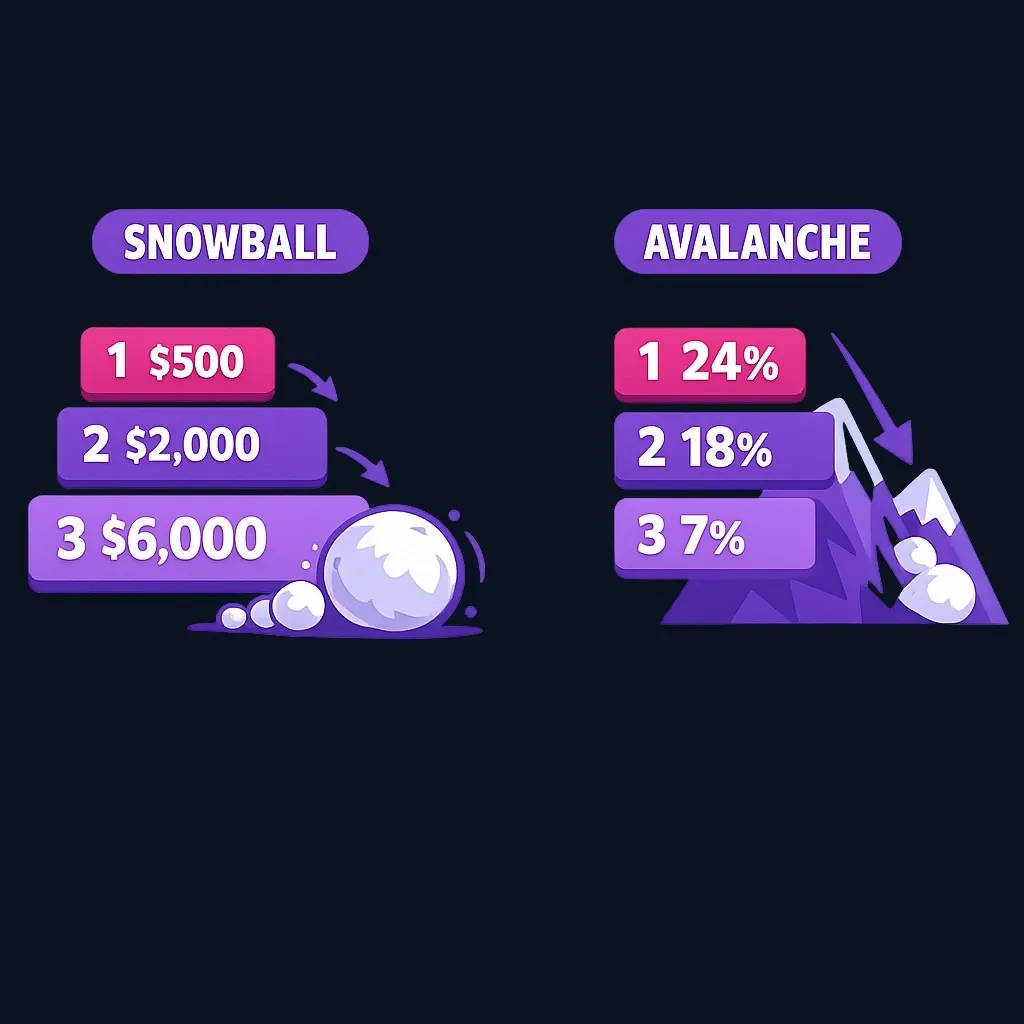
- Mistake: Treating credit as income. Fix: Track credit payments and principal separately; pay off credit balance more aggressively once you have a buffer.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Cutting Expenses & Building an Emergency Fund
Combining expense reduction with a simple savings plan creates immediate and durable relief.
Smart expense reductions (target fixed and variable)
- Fixed-cost strategies (higher impact): negotiate subscriptions and insurance, compare providers annually, downsize when savings outweigh friction.
- Variable-cost strategies (easier short-term wins): reduce dining out, plan grocery lists, carpool or combine errands to save fuel, delay nonessential purchases for 30 days.
Negotiating bills — practical tips
- Call providers before renewal dates and ask for loyalty discounts or hardship options. Prepare: know competing offers and your payment history. If a provider refuses, consider switching only if fees or termination costs are acceptable.
Emergency fund — how to start
- Open a separate, easy-access savings bucket and treat it like a recurring bill. The Consumer Financial Protection Bureau stresses that even small, regular deposits build meaningful security for people without consistent paychecks CFPB guide.
Starter approach (practical)
- Stopgap target: one or two small deposits per pay period (for example, $25–$100) until you have a visible balance.
- Next step: scale payments as discretionary spending shrinks or income grows.
Decision point: how big should the fund be?
- There is no single correct size here; aim first to eliminate the next foreseeable hardship (a car repair, a week of missed work). After you can handle that, increase the fund to cover longer risks.
Checklist for savings automation
- Create a separate savings account or envelope.
- Schedule automatic transfers on payday.
- Use rounding features (round up transactions) if your bank supports them.
- Re-route one discretionary line item to savings each month until the habit sticks.
Increasing Income Through Side Hustles
When cutting costs is not enough, increasing income is the other lever. Side work can be short-term or scalable.
How to choose a side hustle
- Match available time and marketable skills. Prioritize work with predictable pay and low startup cost. Examples of skill-based options include freelance writing, tutoring, or gig-based delivery; choose what fits your schedule and strengths.
Practical plan to start
- Identify two marketable skills or assets (time, space, tools).
- Research local or online demand for short gigs.
- Commit to a trial period (e.g., four weekends) and measure net earnings after expenses and time cost.
- If profitable and sustainable, formalize hours and funnel extra income to savings and debt.
Compounding effect
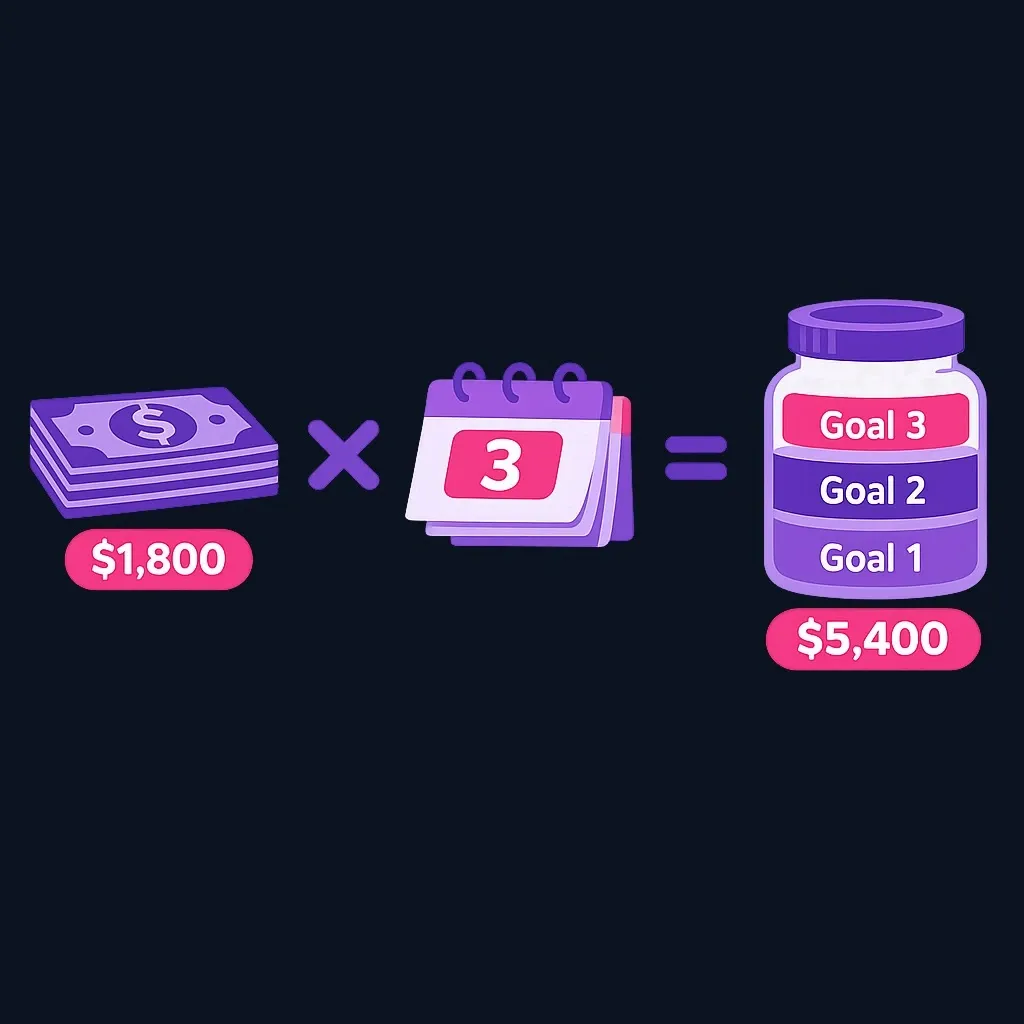
- Even modest, steady extra income can materially reduce the paycheck-to-paycheck gap when it’s consistently applied to savings or high-interest debt.
Caveat: time and taxes
- Treat side income as taxable; set aside a portion for taxes if not withheld. Evaluate whether extra work reduces time for paid employment or increases burnout.
FAQ
What is living paycheck to paycheck?
Living paycheck to paycheck means spending nearly all your earned income each pay period so you have little or no buffer for unexpected costs. It can occur at many income levels if expenses and savings aren’t aligned.
How can I create a budget?
Start by listing net income and every expense for two pay periods, categorize spending into essentials and nonessentials, and assign each dollar a purpose (zero-based budgeting helps). Automate transfers to savings and review monthly to adjust.
How much should I save for emergencies?
Begin with small, regular deposits to a separate account. The Consumer Financial Protection Bureau notes that even a small amount can provide meaningful security for people living paycheck to paycheck; use that initial buffer to cover immediate shocks and gradually increase it CFPB guide.
What are the first steps to stop living paycheck to paycheck?
Track every dollar for two pay cycles, create a simple budget, pause one recurring discretionary expense, set up an automated small transfer to savings, and explore one way to increase income or reduce a major bill.
Conclusion
Stopping the paycheck-to-paycheck cycle combines three durable moves: measure where money goes, build even a small safety buffer, and change recurring patterns that drain cash. Use the decision framework to choose the fastest, lowest-friction actions first, then layer in longer-term changes like negotiating bills and building income streams. Start small, automate where possible, and reassess monthly—consistent, modest improvements compound into financial breathing room.
Sources and Further Verification
Financial LiteracyU.S. GuideFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
What is the 50/30/20 Rule and How to Implement It
If you search for "what is the 50 30 20 rule," it’s a simple budgeting guideline that divides after-tax (take-home) income into three buckets: 50% for needs, 30% for wants, and 20% for savings and debt reduction Consumer Financial Protection Bureau. Use it as a starting template, not…
Finelo Team
Financial Literacy
What is a Grace Period on a Credit Card?
A credit-card grace period is the time between the end of a billing cycle and the payment due date when new purchase balances may not accrue interest if you pay the statement balance in full by the due date. This is the standard definition used by the Consumer…
Finelo Team
Financial Literacy
A Complete Guide to Student Loan Cosigner Release
A cosigner release is a lender-offered process that removes a cosigner’s legal obligation from a private student loan once the primary borrower meets the lender’s conditions—typically a run of on-time payments and a credit check of the borrower alone CFPB. Check your loan documents and contact your servicer…
Finelo Team