For U.S. readers: This article discusses U.S. rules and financial products. State rules and individual eligibility may differ.
VA Funding Fee Refund: Eligibility, Records, and Next Steps
What you should understand after reading this page
5 min read
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Want to learn more?
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Explore FineloExplore Finelo's 28-day challenges
Turn learning into a daily habit with guided challenge paths.
Direct answer
If you were charged the VA funding fee but later become eligible for an exemption (for example, because you receive service‑connected disability compensation), you may qualify for a refund — start by calling the VA Regional Loan Center at (877) 827‑3702 to check eligibility and next steps VA press release. Finelo provides financial education, not financial or investment advice.
Quick comparison answer
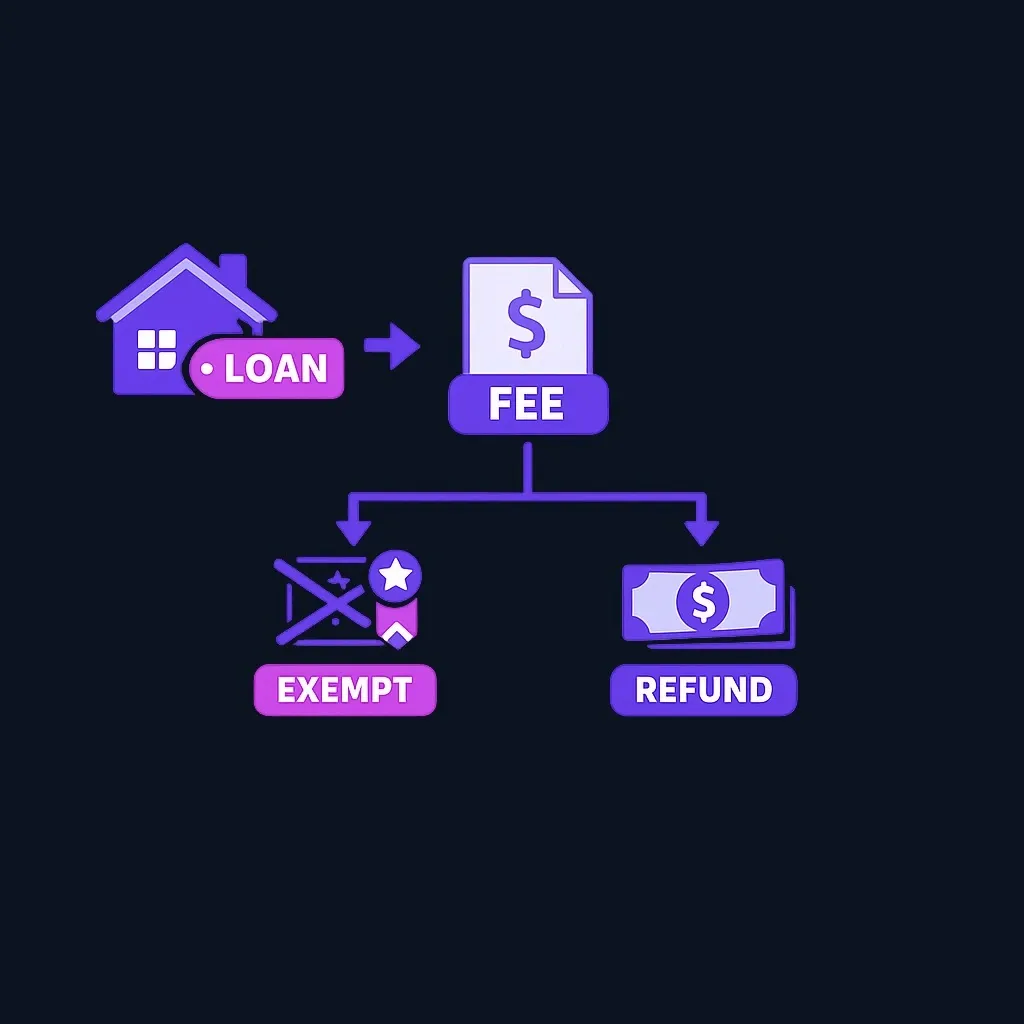
The VA funding fee is a one‑time charge on most VA‑backed home loans intended to lower the VA loan program’s cost to taxpayers; some borrowers are exempt and those later found exempt can seek a refund VA funding fee and loan closing costs. The Department of Veterans Affairs recently completed a refund initiative and issued more than $400 million in funding‑fee refunds to veterans who were entitled to them.
What you should understand after reading this page
- Who commonly qualifies (overview) and how to check eligibility. See the Steps section for immediate actions.
- What to prepare before you call the VA or your lender.
- How to escalate or appeal if your request is denied.
Steps to solve it
Follow this practical sequence to check eligibility and request a refund.
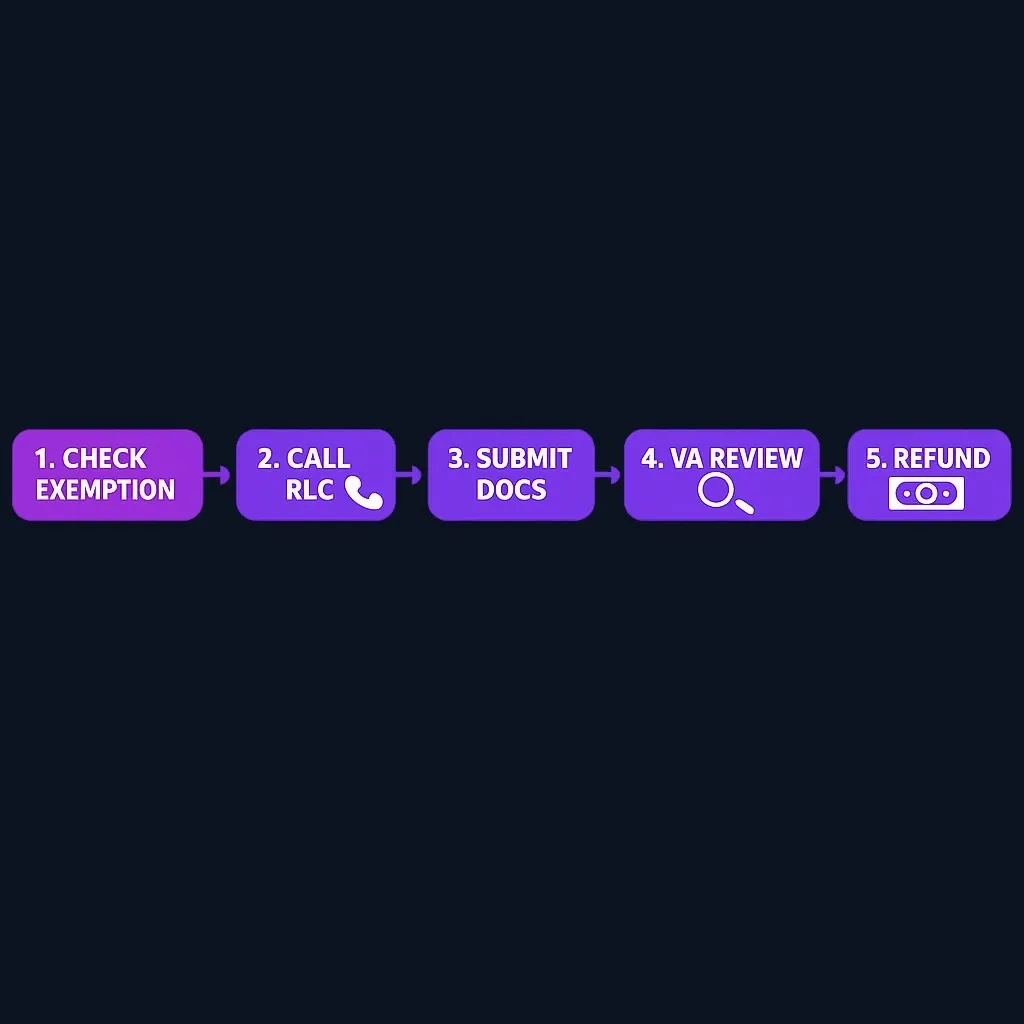
- Confirm the reason you think you qualify. Exemptions are most often tied to VA disability status or other VA entitlement rules; check the VA funding‑fee overview for exemption categories.
- Call the VA Regional Loan Center. The VA asks veterans who believe they are owed a refund to call the VA Regional Loan Center at (877) 827‑3702 to determine eligibility and next steps.
- Ask which documents the VA or your lender requires. The VA or your lender will tell you the specific evidence needed and how to submit it; requirements can vary by situation.
- Submit the requested documents and keep copies. Follow the submission method the VA or your lender specifies (mail, fax, or secure upload).
- Confirm receipt and ask for a timeline and reference number so you can track progress.
Simple flow (visualized as steps)
- Check whether an exemption or new disability rating applies → Call VA Regional Loan Center at (877) 827‑3702 → Provide requested documentation → VA/lender reviews → VA issues refund if eligible.
Quick checklist before you call
- Loan number or mortgage account number (if available).
- Closing date and the amount of funding fee charged (from your Closing Disclosure or HUD‑1).
- Any VA award letter or disability rating notice you recently received (if applicable). Note: these are commonly‑requested items — confirm the exact list with the VA Regional Loan Center when you call.
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
Troubleshooting
This section covers common delays, how to avoid them, and what to do if a refund is denied.
Common documentation errors that delay refunds
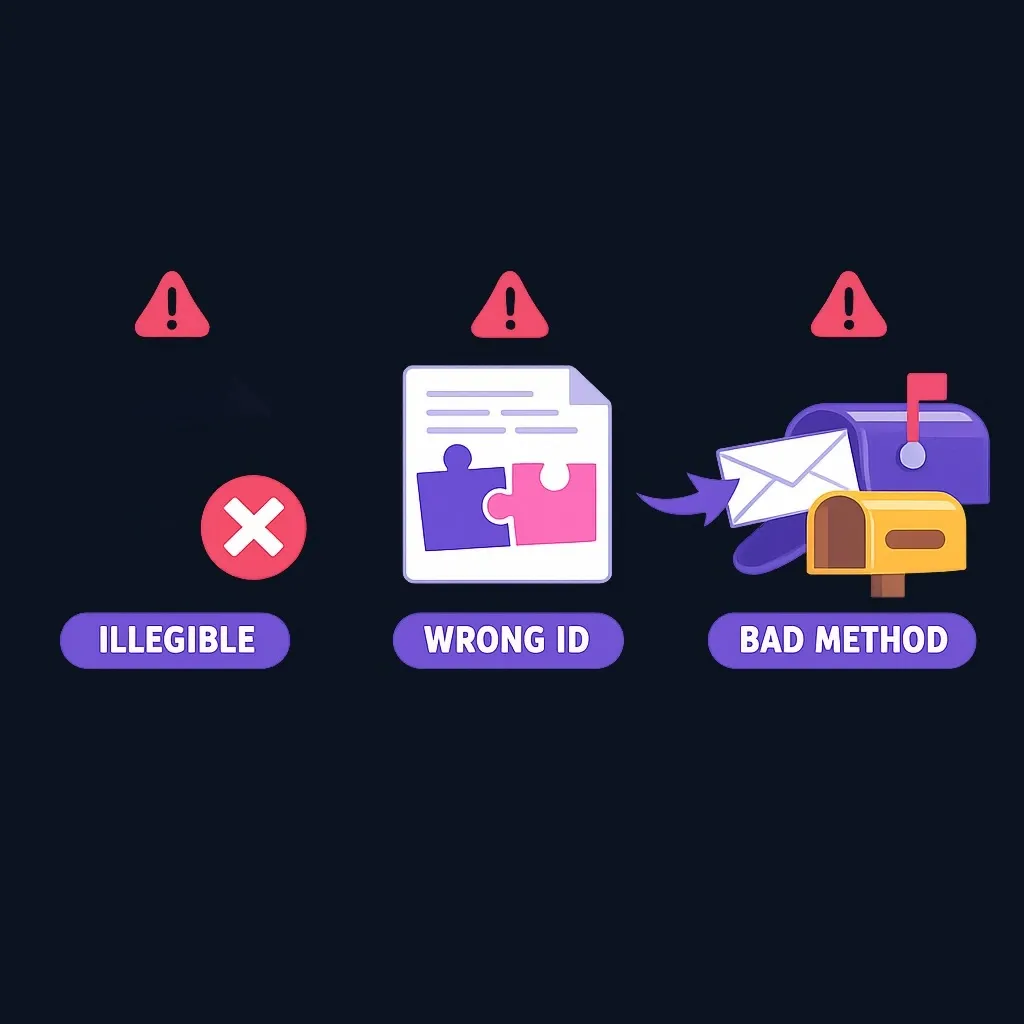
- Missing or illegible pages: send clear, complete copies and verify every page is readable.
- Wrong account identifiers: include the loan number, veteran full name, and closing date to tie documents to the correct file.
- Not following submission instructions: if the VA or lender requests a signed form or original, confirm acceptable alternatives first. Practical tip: ask the staff member taking your call to read back the documents they need and the preferred submission method.
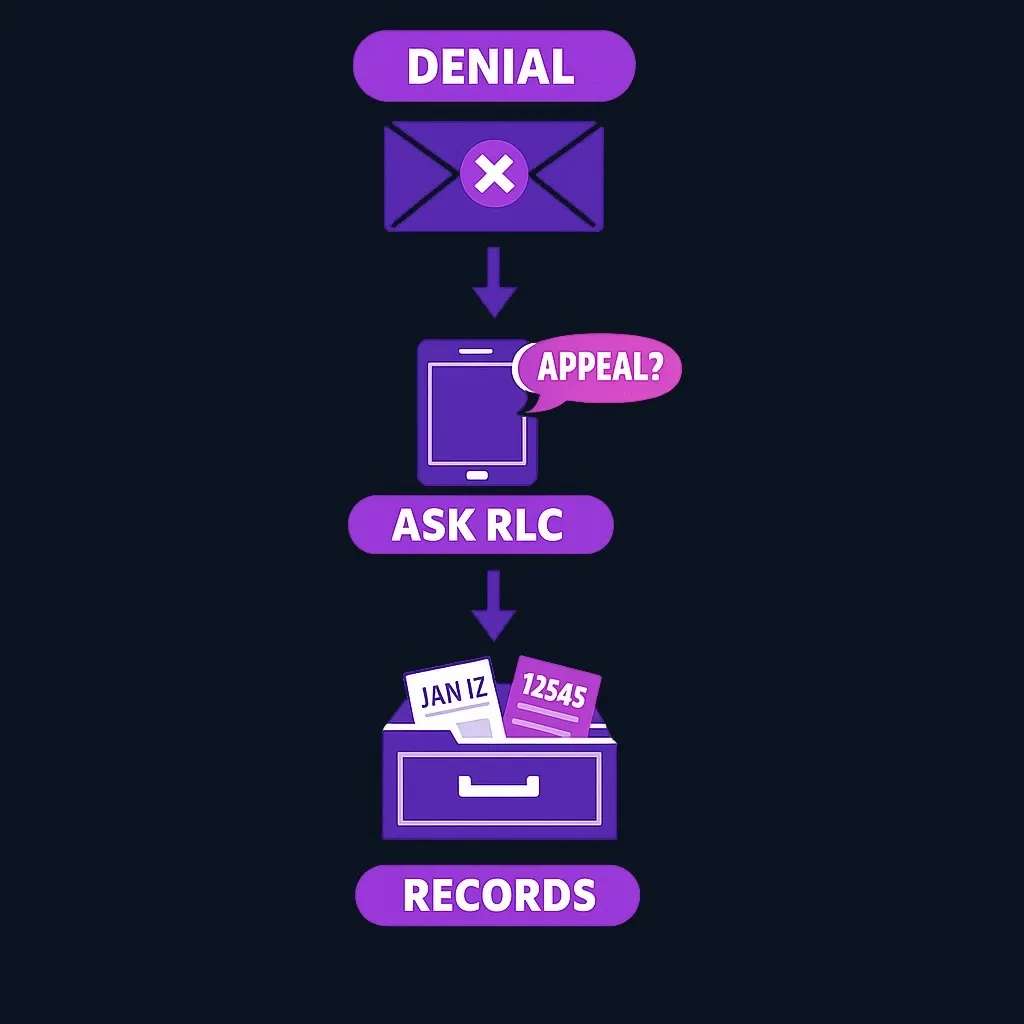
If your refund request is denied
- Request a written explanation stating why the refund was denied and which evidence would change the decision.
- Ask the VA Regional Loan Center for the specific process to request reconsideration or next steps; the RLC is the VA point of contact for funding‑fee questions.
- Keep copies of every communication and submission; track dates, names, and reference numbers.
Tracking your refund status
- Use the VA Regional Loan Center phone number to check status and ask for a reference or ticket number you can quote in future calls.
- If your lender was involved (for example, the fee was financed into your loan), confirm whether the lender will adjust your loan account and whether the VA will issue the cash refund to you; ask both parties to document any agreed action.
Related help links
- VA — Funding Fee and Loan Closing Costs (overview of funding fee and exemptions): https://www.va.gov/housing-assistance/home-loans/funding-fee-and-closing-costs/
- VA News — VA completes home loan funding fee refund initiative (RLC contact and refund initiative): https://news.va.gov/press-room/va-completes-home-loan-funding-fee-refund-initiative/
- Finelo — further financial education and resources: Finelo Blog
For educational material on VA loan basics before contacting the VA or a lender, explore Finelo Blog.
FAQ
What is the VA funding fee?
The VA funding fee is a one‑time charge applied on most VA‑backed or VA direct home loans; certain borrowers are exempt from the fee under VA rules.
Who should I call to find out if I’m due a refund?
The VA advises veterans who believe they are entitled to a refund to call the VA Regional Loan Center at (877) 827‑3702 to determine eligibility and next steps.
What should I have ready when I request a refund?
Have your loan or account number, closing date, and any new VA documentation (for example, a VA disability rating or award notice) available. Confirm with the VA Regional Loan Center exactly which documents they require and how to submit them.
How long will a refund take?
Processing times vary by case, documentation, and whether the fee was paid in cash or financed; ask the VA Regional Loan Center for an estimated timeline when you call and request a reference number to track your request.
If you’re ready to learn more about VA loan basics or want guidance on documents to gather before you call, visit the Finelo Blog: Finelo Blog
Financial LiteracyFinancial Education
Practice trading with Finelo
Practice in a simulator, learn with bite-sized lessons, and build confidence before risking real money.
About the author
Finelo Team
The Finelo Team creates practical investing and trading education designed to help beginners learn faster with structured challenges, simulator practice, and bite-sized lessons.
Keep reading — Related articles
Financial Literacy
Mercury Books Review 2026: Is It Worth It for Startups?
Mercury Books brings double-entry accounting into Mercury. Review its $35 pricing, reports, AI features, integrations, and migration limits.
Finelo Team
Financial Literacy
Why is My FICO Score Lower Than My Credit Score?
Example takeaway: seeing a higher score in a bank app doesn’t guarantee lenders will see the same FICO number at application time; lenders often pull a specific FICO version from a specific bureau.
Finelo Team
Financial Literacy
Why Is My FICO Score Higher Than My Credit Score?
Brief educational note: this article is educational, not financial or investment advice; investing and credit decisions involve risk and possible loss.
Finelo Team


